
Manchester guide
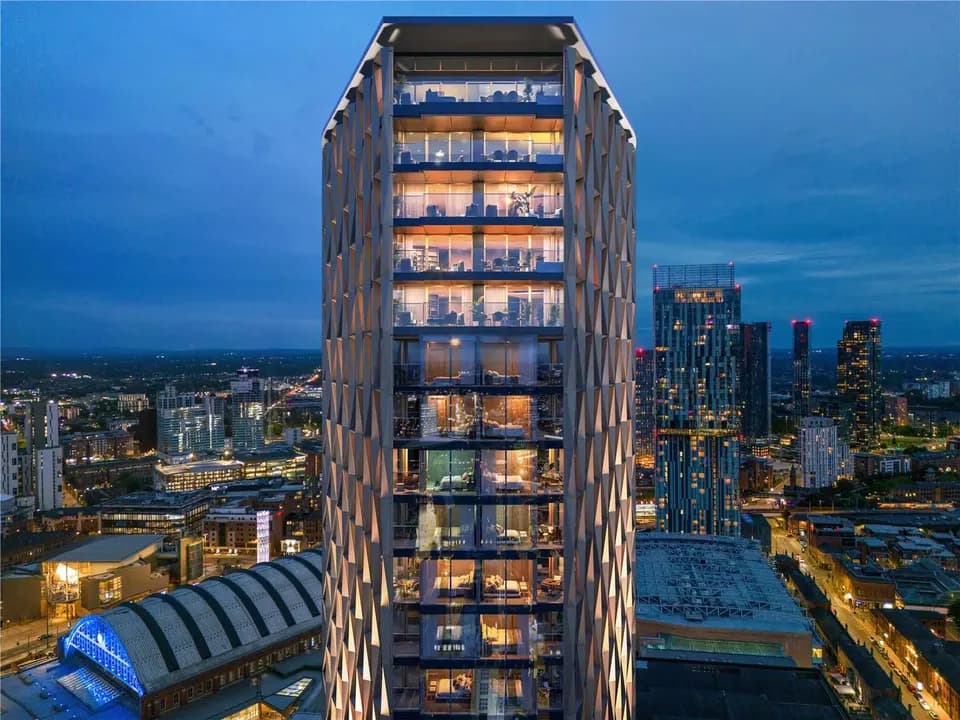
Off-plan property for sale in Manchester.
New-build and off-plan apartments in Manchester for overseas investors: the developments we sell, how payment plans and deposit protection work, and how to choose a scheme that completes into a tight market.
- Buy at launch pricing and choose the best units: aspect, floor and layout go first in a new release.
- Completing into a thin pipeline: city-centre homes under construction fell to 8,023 in 2026, the lowest since 2016 (Deloitte Crane Survey).
- Protected properly: deposits held by your solicitor, a 10-year structural warranty and a regulated sales process.
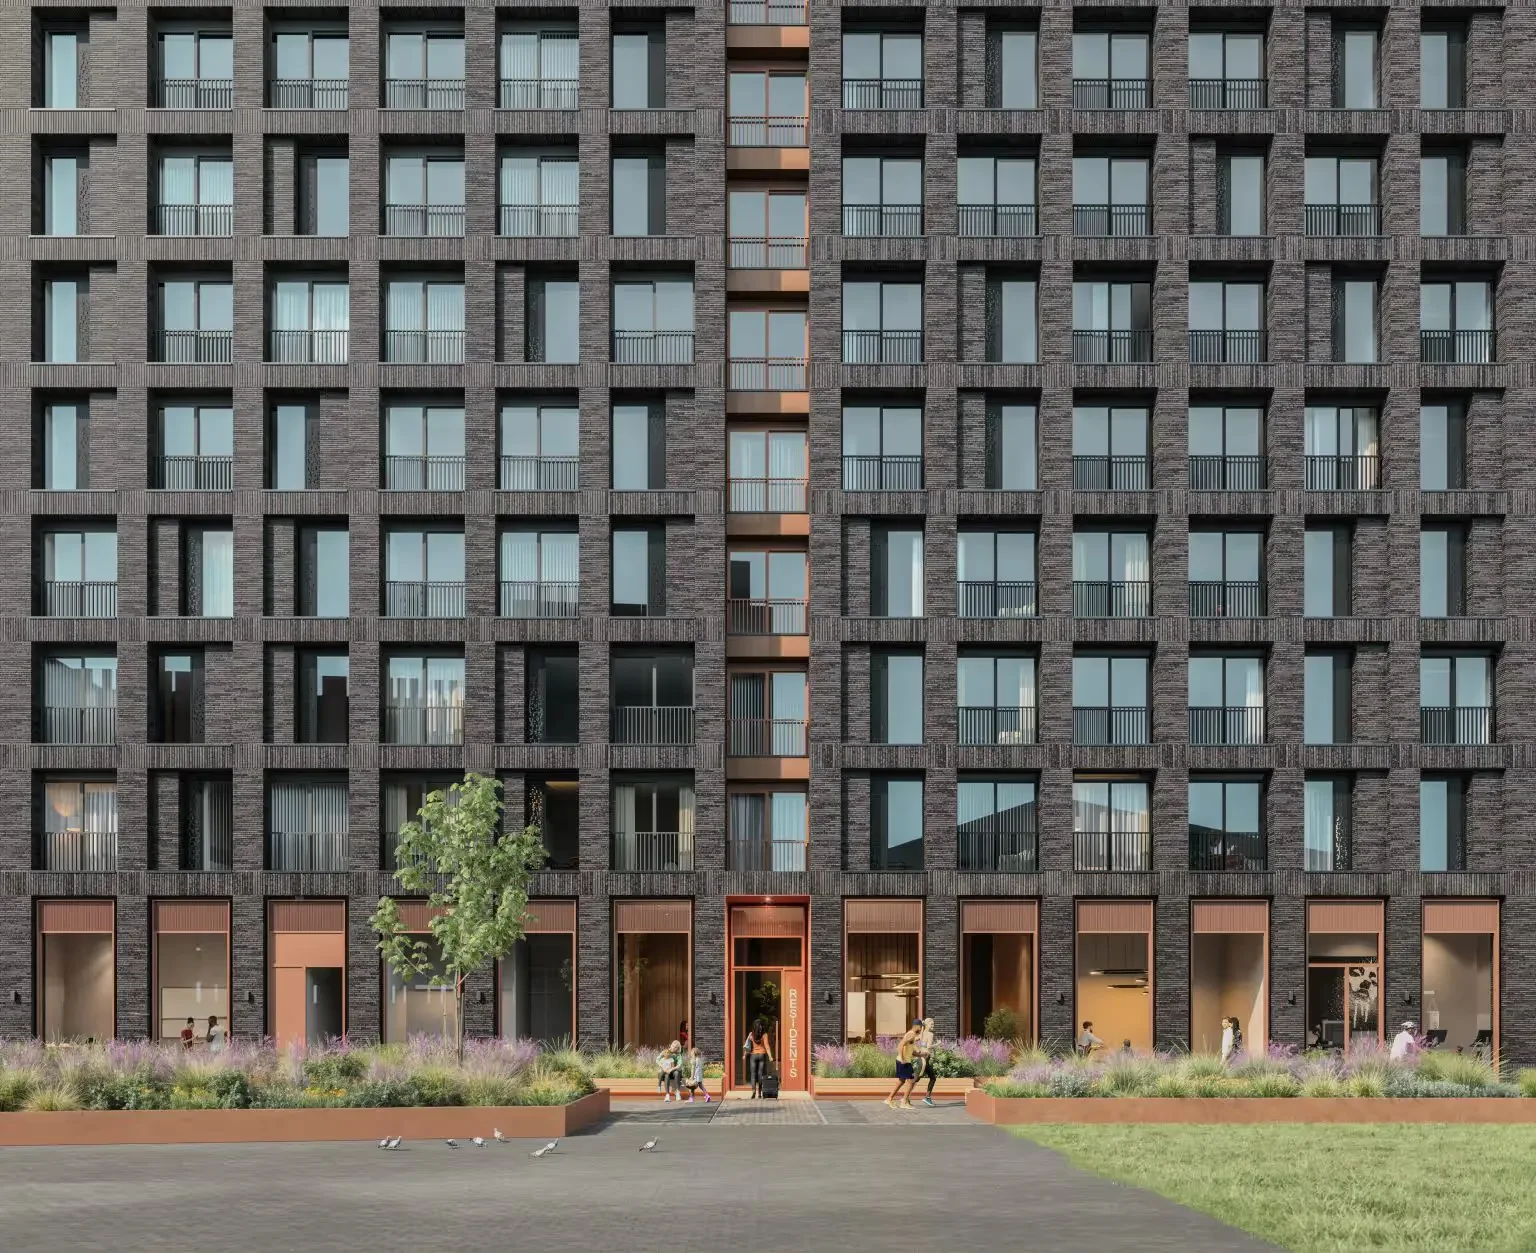
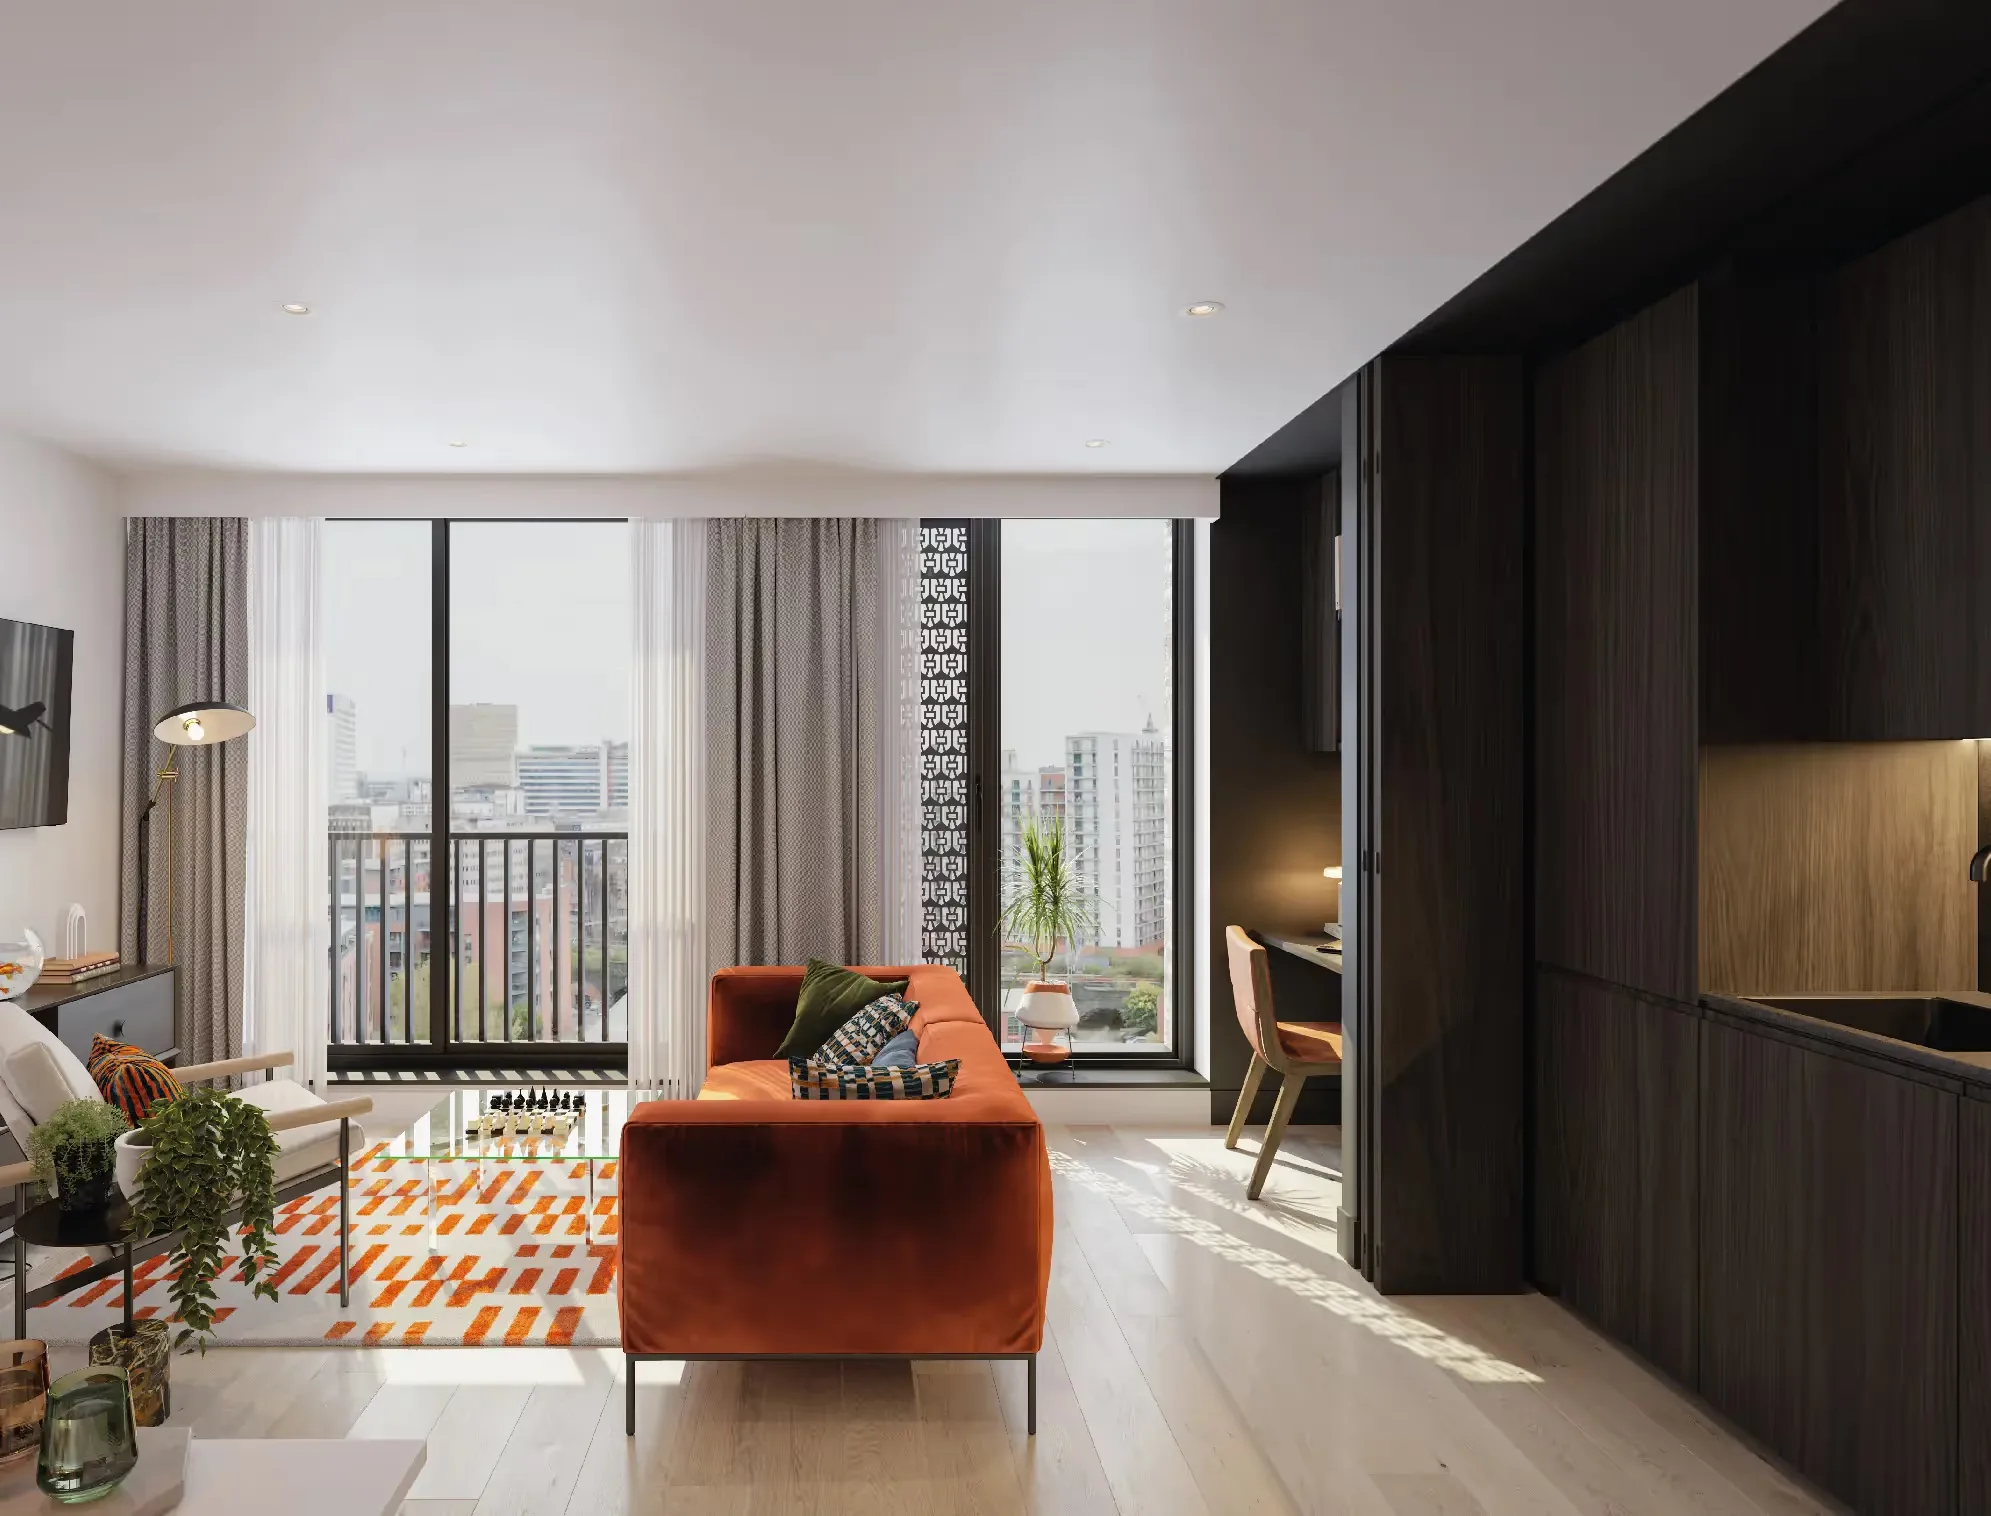
Off-plan is how most overseas investors buy in Manchester. You reserve an apartment before or during construction, pay in stages, and complete when the building is finished. Done well, it gives you launch pricing, the pick of the units and a completion timed into a market where new supply is falling. Done badly, it ties your money up in the wrong building. This page covers the developments we sell and how to choose.
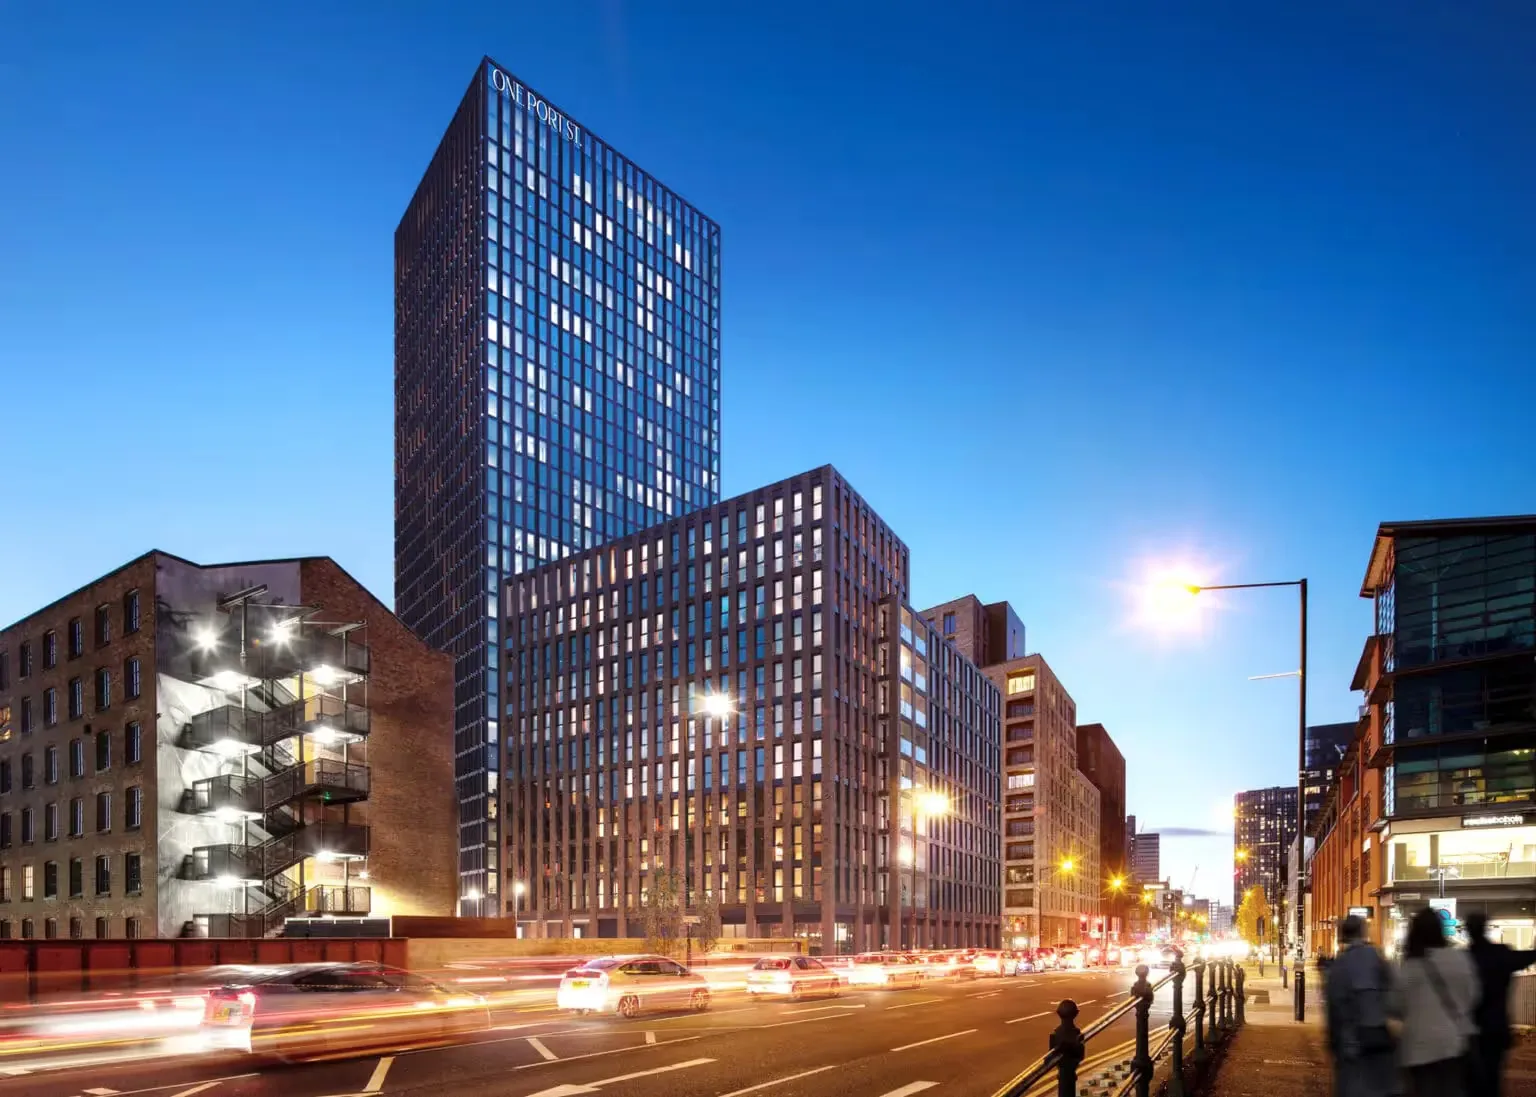
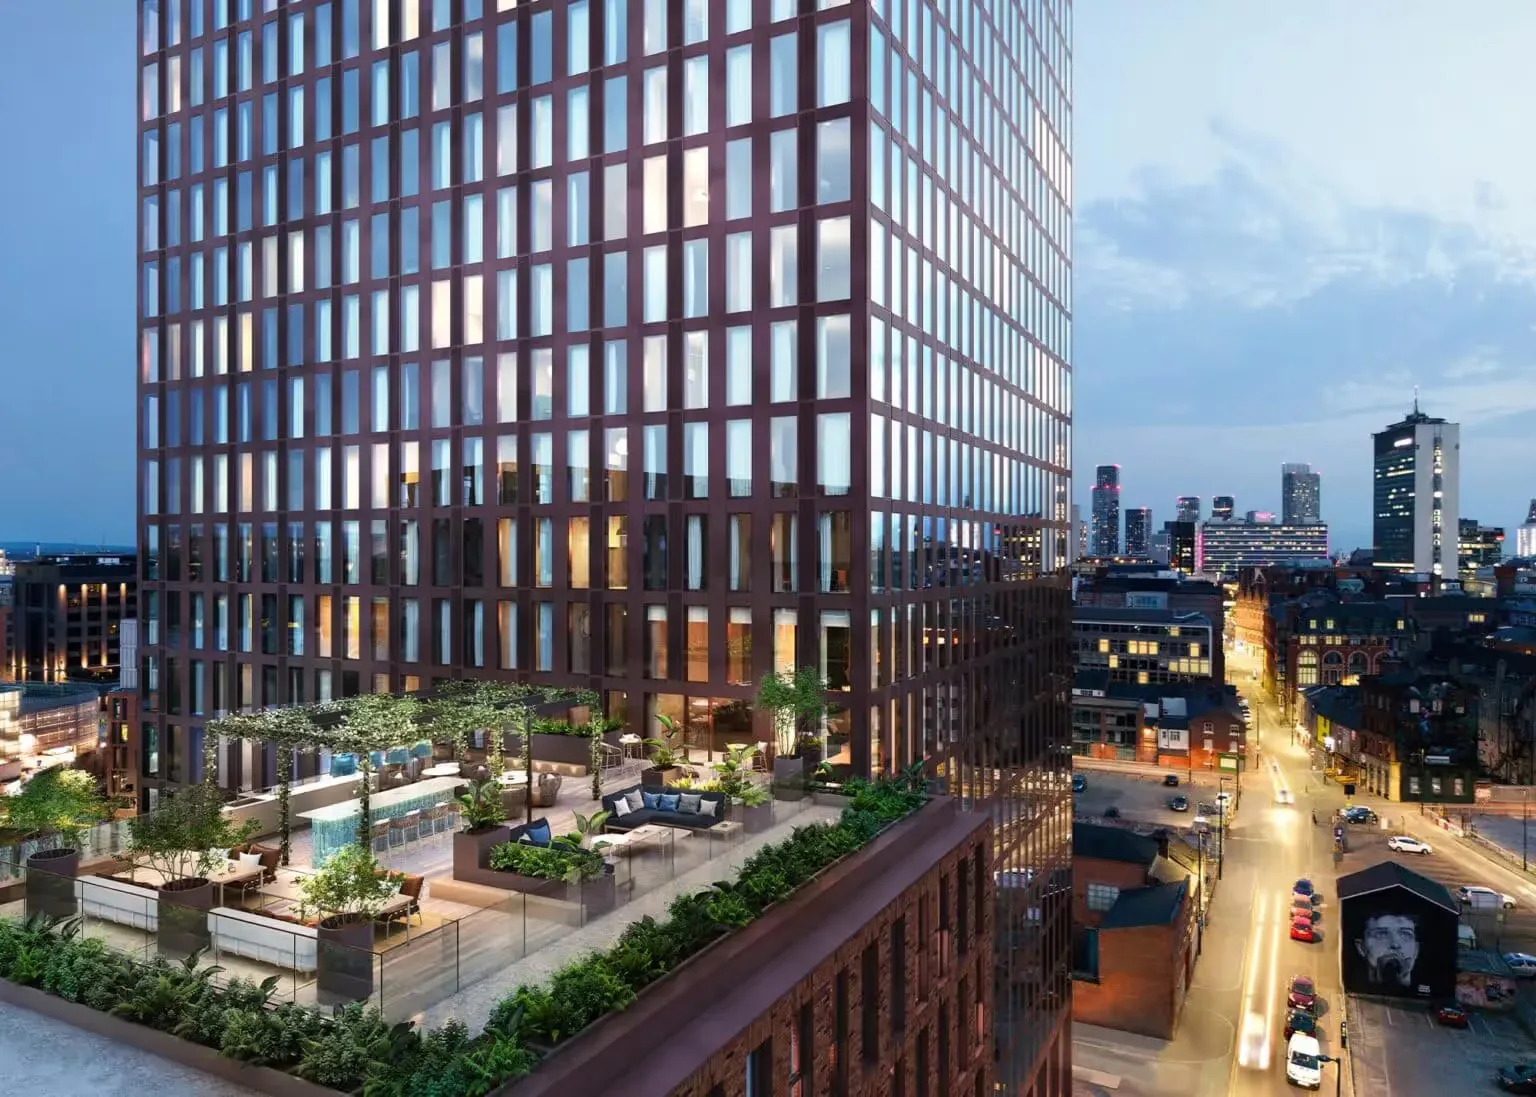
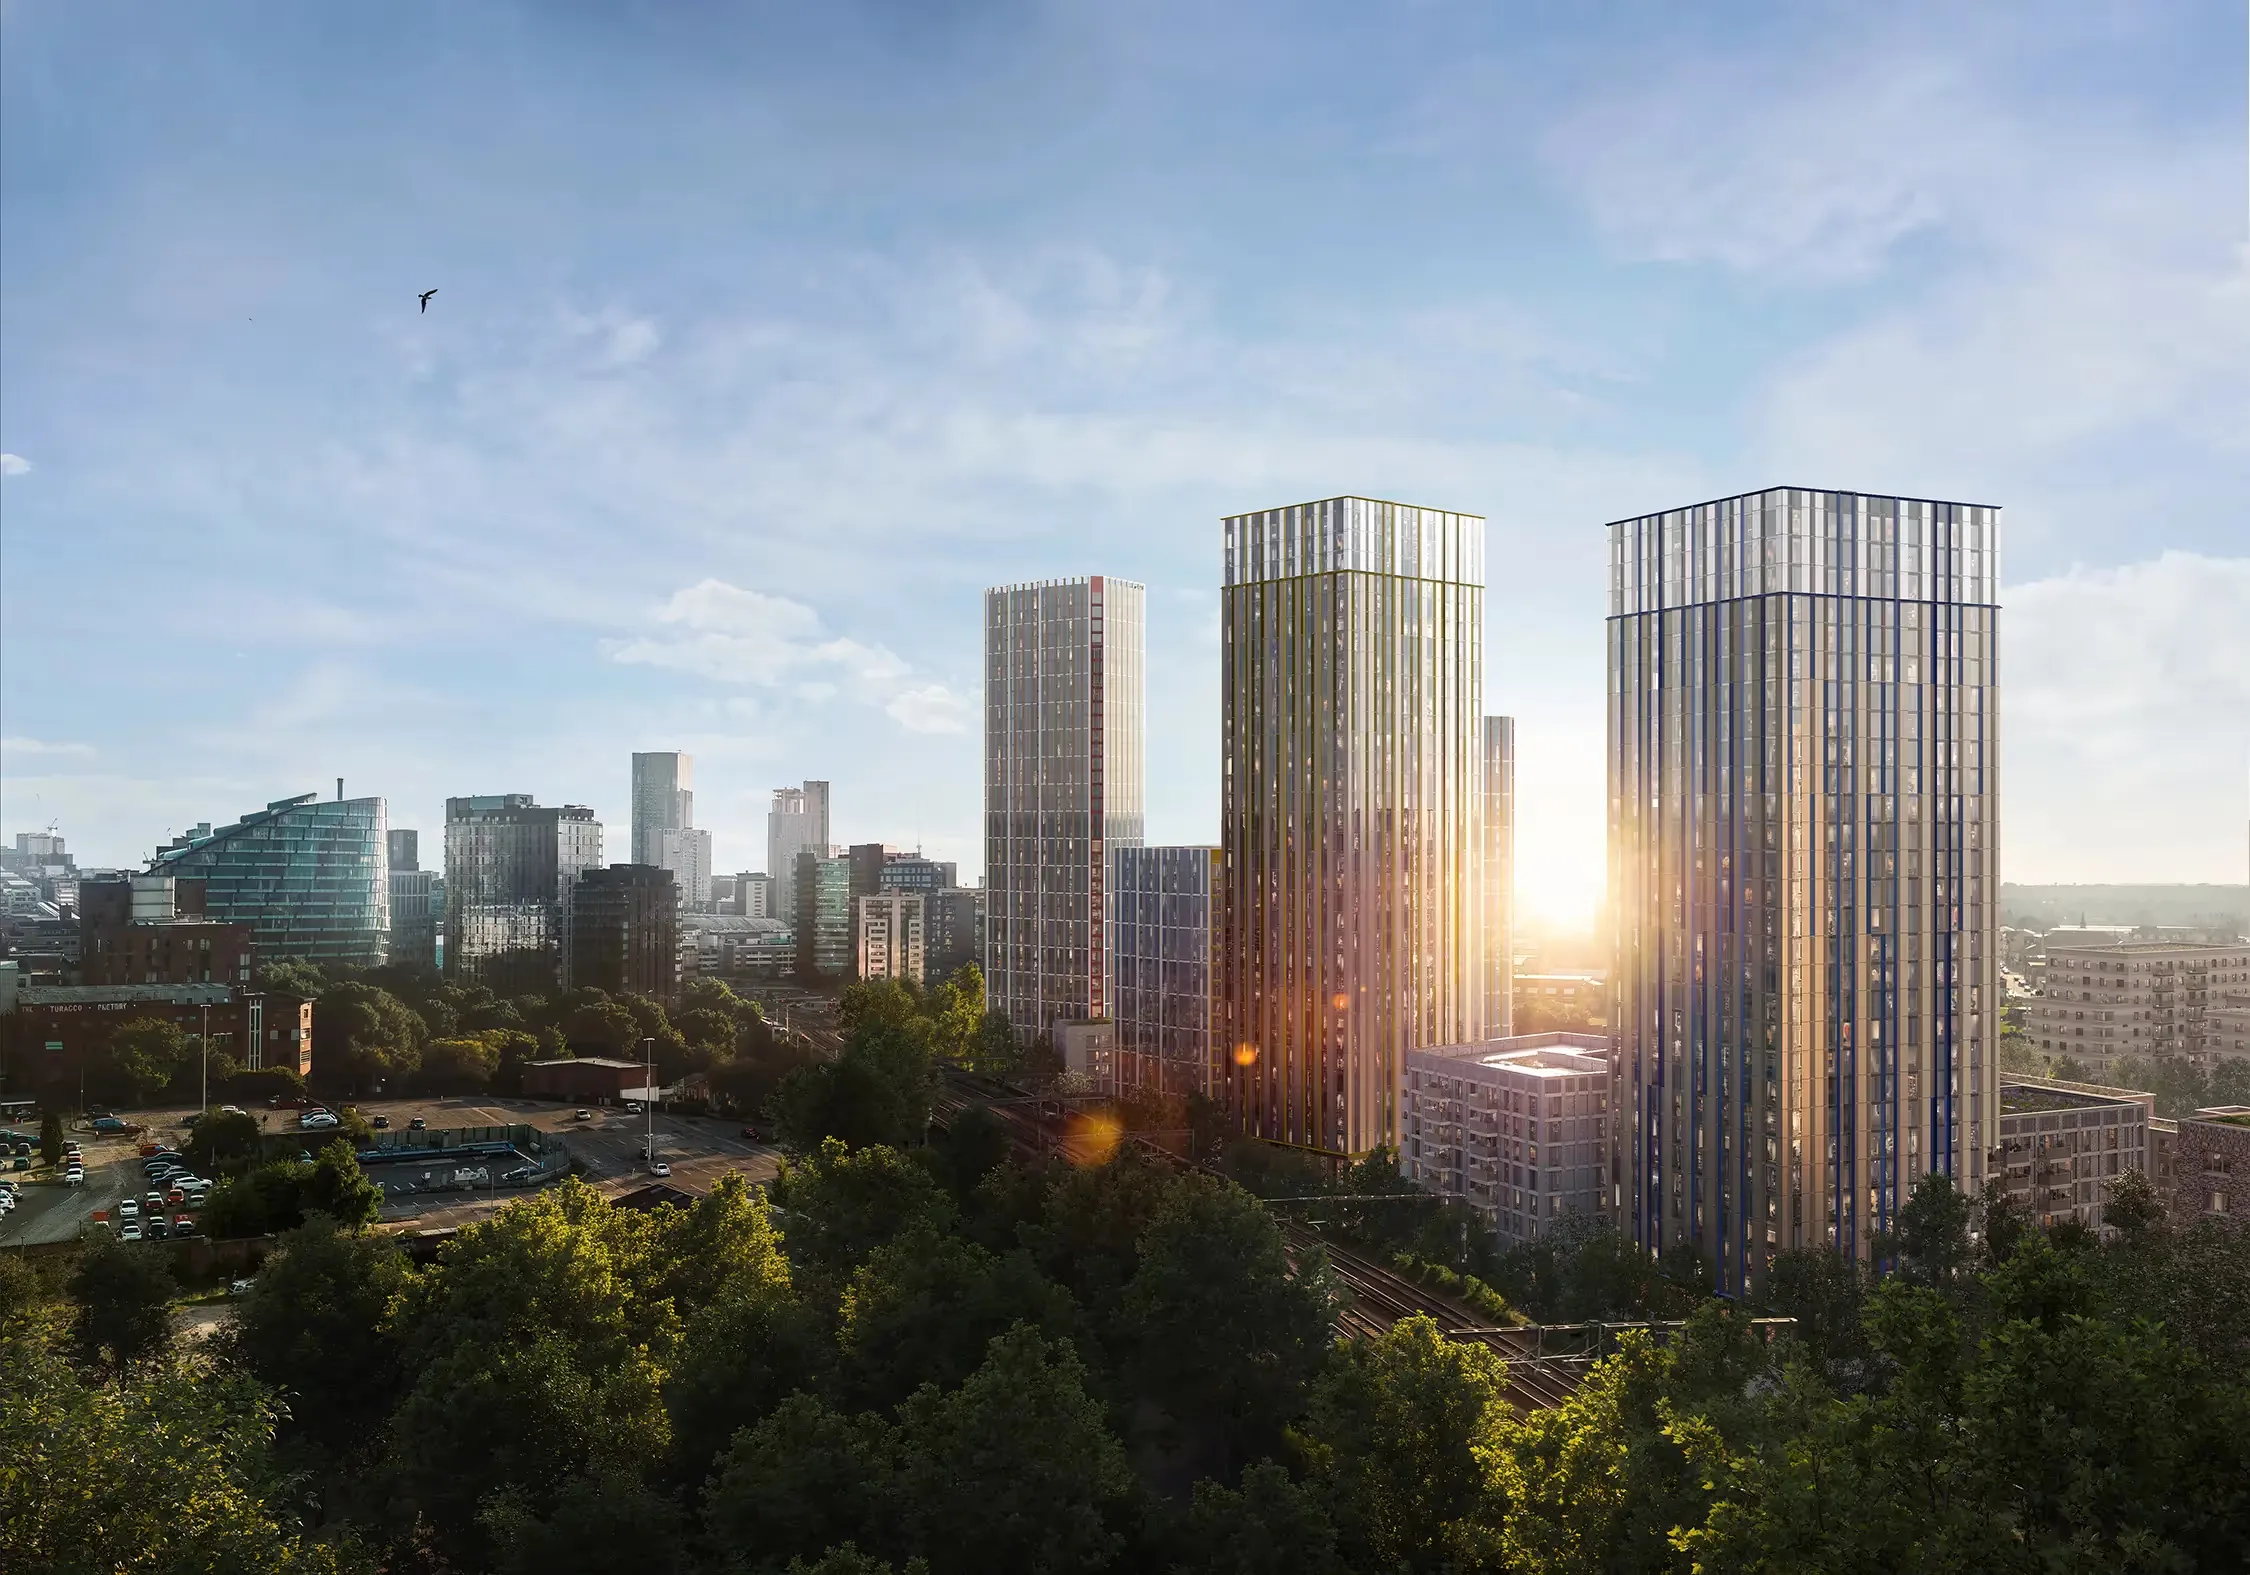
The developments Continental currently lists in Manchester are shown on this page. If none fits, tell us the brief and we will search the wider market for you.
How buying off-plan in Manchester works
- Reservation. A reservation fee, typically a few thousand pounds, takes the unit off the market while solicitors are instructed.
- Due diligence. Your solicitor reviews the lease, the planning, the build contract terms and the warranty, and completes anti-money-laundering checks on you and your funds.
- Exchange. You sign the contract and pay the first deposit, commonly 10% or more of the price, held by the developer's solicitor under the contract's terms.
- Staged payments. Some schemes ask for further instalments during the build; others ask for nothing more until completion.
- Snagging and completion. You (or we) inspect the finished unit, defects are fixed, and you pay the balance, in cash or with a mortgage arranged close to completion.
- Letting. With the right agent lined up, tenants can move in within weeks of completion.
Typical payment structures
Structure | How it works | Suits |
|---|---|---|
10% at exchange, 90% at completion | One deposit, balance on keys | Mortgage buyers |
20% to 30% over the build | Deposit plus staged instalments | Cash buyers spreading payments |
Extended plans | Smaller instalments over a longer period | Buyers preferring lower upfront outlay |
Payment terms vary by scheme. The figures on each development page are the developer's terms at the time of listing.
How your money is protected
- Solicitors. Deposits are paid to solicitors and handled under the contract and professional rules, not handed to a sales agent.
- Warranty. New homes come with a 10-year structural warranty from providers such as NHBC, Premier Guarantee or LABC Warranty. Lenders require one.
- Consumer codes. Developers registered with the New Homes Quality Board or the Consumer Code for New Homes must follow rules on information, deposits and complaints.
- Long-stop date. The contract sets a final date by which the building must complete, with your right to rescind and recover your deposit if it does not. Check it.
Choosing a Manchester scheme
Check | Why it matters |
|---|---|
Developer delivery record | Completed buildings on time are the best predictor |
Location against regeneration | Completing into a district that is filling up lifts values |
Service charge estimate | Decides your net yield for years |
Layout and aspect | Two-bed, two-bath and good light let and resell best |
Completion date | 2027–2029 completions arrive as the pipeline is thinnest |
Rent evidence | Compare with completed buildings nearby, not the brochure |
Off-plan versus completed stock
Off-plan offers launch pricing, unit choice and time to arrange finance. Completed stock offers rent from day one and no construction risk. Many of our investors hold both: completed or near-complete stock for income, off-plan for growth.
Costs to plan for
Stamp duty is paid at completion, not at exchange. For a non-resident buying an additional home it is the standard rate plus 7%, which is £20,000 on a £250,000 apartment. Add legal fees, mortgage costs if any, and furnishing. See UK property taxes for overseas buyers or work out your stamp duty.
The Manchester guide · Buy-to-let in Manchester · Buying property in the UK from overseas
More in our Manchester guide and the United Kingdom investment guide.