
Manchester guide
Buy-to-let in Manchester: the investor's playbook.
How to buy a Manchester rental property from overseas and make it pay: the numbers, the stock that lets, the areas, the finance, the tax and the new rules for landlords.
- Rent first. Manchester rents rose 4.2% in the year to August 2026 to £1,373 a month (ONS); a well-chosen apartment pays its way from completion.
- Two-bed, two-bath apartments in walkable central districts are the most liquid buy-to-let product in the city: they suit sharers, couples and corporate tenants.
- The rules changed in 2026. Periodic tenancies under the Renters' Rights Act reward good stock and good management and penalise everything else.
Buy-to-let is the reason most overseas investors buy in Manchester. The city's tenant base is large, young and still growing, rents are rising faster than prices, and a central apartment can be let, managed and eventually sold without you ever needing to visit. This playbook covers each decision in the order you will make it.
1. Start from net, not gross
Manchester's average rent was £1,373 a month in August 2026, up 4.2% in a year, against an average price of £252,000 (ONS). That is a gross yield of about 6.5%, and it is where most marketing stops. A landlord's return is what is left after the service charge, management, voids and upkeep, and the service charge alone can move a typical apartment's net yield from 4.8% to 4.2%. Set your target as a net figure and work back to the price you can pay. Manchester rental yields shows the figures by neighbourhood and building type.
2. Choose the right product
Product | Tenant | Why it works |
|---|---|---|
Two-bed, two-bath apartment | Sharers, couples, corporate lets | Highest demand, rent per room, easy resale |
One-bed apartment | Single professionals | Low entry price, quick to let |
Studio | Students, graduates | Highest gross yield, highest turnover |
Townhouse or family house | Families, relocations | Longer tenancies, often better capital growth, more maintenance |
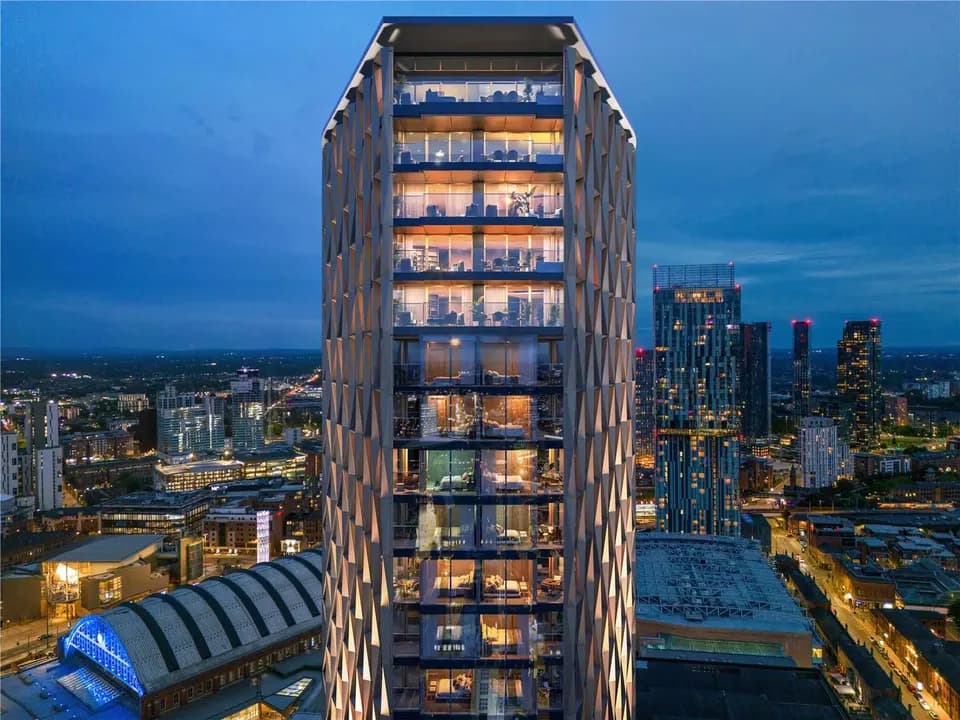
For a hands-off overseas landlord, the modern two-bed apartment in a managed building is the default choice. It is what the deepest pool of tenants wants, and it is the easiest unit to sell on to another investor or an owner-occupier.
3. Pick the area
Yield and safety pull in opposite directions. The established core (Spinningfields, Deansgate, Ancoats, the Northern Quarter) gives you the strongest tenants and the lowest voids at a higher entry price. Salford, Victoria North and Old Trafford give you a lower price and a higher gross yield, with more reliance on regeneration delivering. Compare them in where to buy in Manchester.
4. New-build, off-plan or resale
- Off-plan buys at launch pricing with staged payments, and you choose the unit. You wait for income, and you take completion risk. See off-plan property for sale in Manchester.
- New-build at completion lets immediately, with a 10-year structural warranty and modern energy performance.
- Resale can be cheaper per square foot, but check the building-safety position and the service charge history carefully.
5. Finance it
Non-resident buy-to-let mortgages are widely available but cost more and ask for more equity than domestic ones: typically 25% to 40% deposit. HSBC, for example, asks non-residents for at least 25%, more on the largest loans, and a minimum income of £50,000. Lenders stress-test the rent against the loan, so the property must stand on its own numbers. For off-plan, arrange the mortgage close to completion, because offers expire. Read UK mortgages for overseas buyers.
6. Budget for tax
- Stamp duty: standard rates plus 5% on additional homes plus 2% for non-residents. £20,000 on a £250,000 purchase. Work out yours.
- Income tax: on rental profit, at 22%, 42% or 47% from April 2027. Under the Non-Resident Landlord Scheme your agent deducts 20% unless HMRC approves you to receive rent gross.
- Capital gains tax: at 18% or 24% on a sale, reported within 60 days.
Owning through a company changes the picture, for better or worse depending on your circumstances. Take advice before you buy. See UK property taxes for overseas buyers.
7. Let it under the new rules
Since 1 May 2026 the Renters' Rights Act has applied in England. Section 21 "no-fault" evictions have ended, tenancies are periodic, and a private rented sector database and landlord ombudsman are being introduced. In practice:
- Use a professional, accredited letting agent and keep every compliance certificate current: gas safety, electrical inspection, EPC, deposit protection, right to rent.
- Price at the market. Tenants can now leave on two months' notice, so an over-priced unit risks a void.
- Good buildings with good management keep tenants for longer, which now matters more than ever.
8. Plan the exit
Most investors hold Manchester apartments for five to ten years. The cleanest exits are units another investor can buy with the tenant in place, or that an owner-occupier will want: good layouts, sensible service charges, buildings with clear safety paperwork.
Mistakes we see
- Buying on gross yield and discovering the service charge.
- Buying the cheapest unit in a building: north-facing, low floor, by the lifts.
- Assuming rental guarantees replace real demand. Check what the building's completed units actually let for.
- Forgetting the 7% of stamp duty surcharges when calculating return.
- Skipping building-safety checks on a resale flat, then failing to sell or remortgage.
The Manchester guide · Manchester property forecast · Buying in the UK from overseas
More in our Manchester guide and the United Kingdom investment guide.