
In this story6 chapters
American buyers have more reasons than ever to look abroad: a strong dollar in many markets, lifestyle ambitions and portfolios heavy in US assets. Off-plan property, bought before or during construction, is often the most efficient way in. This is how it works, what the IRS expects, and where it suits.
How off-plan works
You reserve a unit in a development that is not yet finished, at a price fixed today, and pay in stages. The shape of the payment plan varies by market.
- Deposit and balance. Often 20–30% down and the rest at handover, common in Thailand and Malaysia.
- Construction-linked. Payments staged as the building rises, typical in the Gulf.
- Post-handover. Part of the price paid over years after completion, sometimes from the rent.
The appeal is that your money goes in gradually, and you buy at launch pricing. The risk is that you are paying for something that does not yet exist. Use the planner below to see what leaves your account, and when.
Interactive · Payment planner
What you pay, and when
Set a price and a plan. The timeline shows every payment from reservation to keys.
Staged through construction. The Gulf’s standard shape.
| When | Payment | Amount |
|---|---|---|
| Today | Reservation and deposit | US$40,000 |
| Month 5 | Construction stage 1 of 5 | US$40,000 |
| Month 10 | Construction stage 2 of 5 | US$40,000 |
| Month 15 | Construction stage 3 of 5 | US$40,000 |
| Month 20 | Construction stage 4 of 5 | US$40,000 |
| Month 25 | Construction stage 5 of 5 | US$40,000 |
| Month 30 | Handover balance | US$160,000 |
Checking the developer
The developer matters more than the brochure. Before you reserve:
- Track record. How many projects has the developer completed, and were they on time?
- Deposit protection. Find out where your money is held. Escrow or a solicitor’s client account is the standard to ask for.
- Title and permits. Confirm the land title, the building permit and, in Thailand, the remaining foreign quota.
- The contract. Have an independent local lawyer read it, especially the clauses on delays and specification changes.
- Exit. Ask whether you can assign the contract before completion, and at what cost.
Your US tax obligations
Buying abroad does not take you outside the US tax system. Americans are taxed on worldwide income, and several rules apply to property overseas.
- Rental income is reported on Schedule E, just as for a US rental.
- Depreciation of a foreign residential rental is straight-line over 30 years under the alternative depreciation system, with no bonus depreciation.
- Foreign income tax paid on the rent can usually be credited on Form 1116. Foreign property tax is deducted, not credited.
- FBAR. If your foreign bank accounts total more than $10,000 at any time in the year, report them to FinCEN.
- Form 8938. Specified foreign financial assets above set thresholds must also be reported. Property held directly is generally not one of them; accounts and foreign companies are.
- FIRPTA is not your concern as a buyer abroad. It applies to foreign persons selling US property.
These are the headlines, not advice. A US tax adviser with international clients will save you more than they cost.
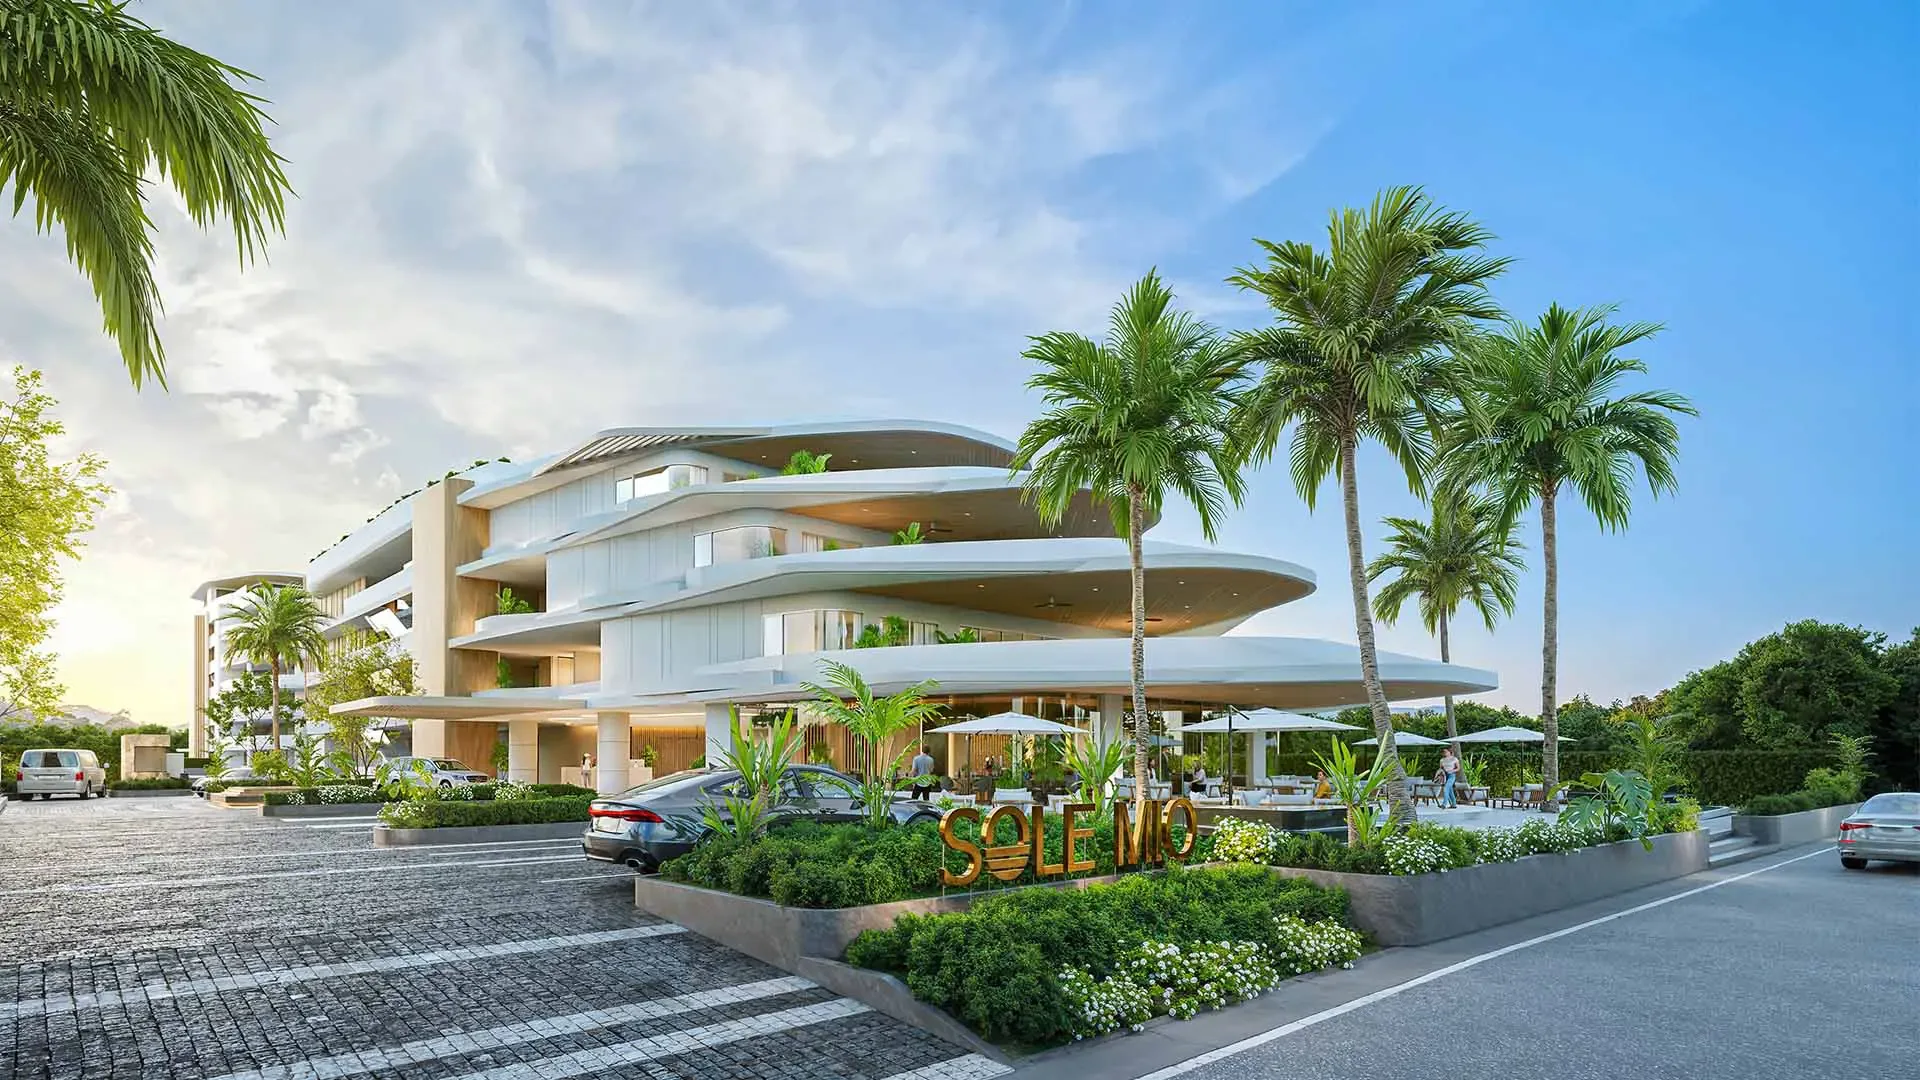 On the market in ThailandSole Mio ResidencesPhuket, ThailandFrom THB 20,200,000See the development
Where American buyers fit
Our markets treat Americans as they treat any foreign buyer. In Thailand the Treaty of Amity covers business ownership, not land, so Americans buy under the standard rules: freehold condominiums within the 49% quota, and leasehold for land. In 2025 Americans bought 537 Thai condominium units, the sixth-largest group of foreign buyers.
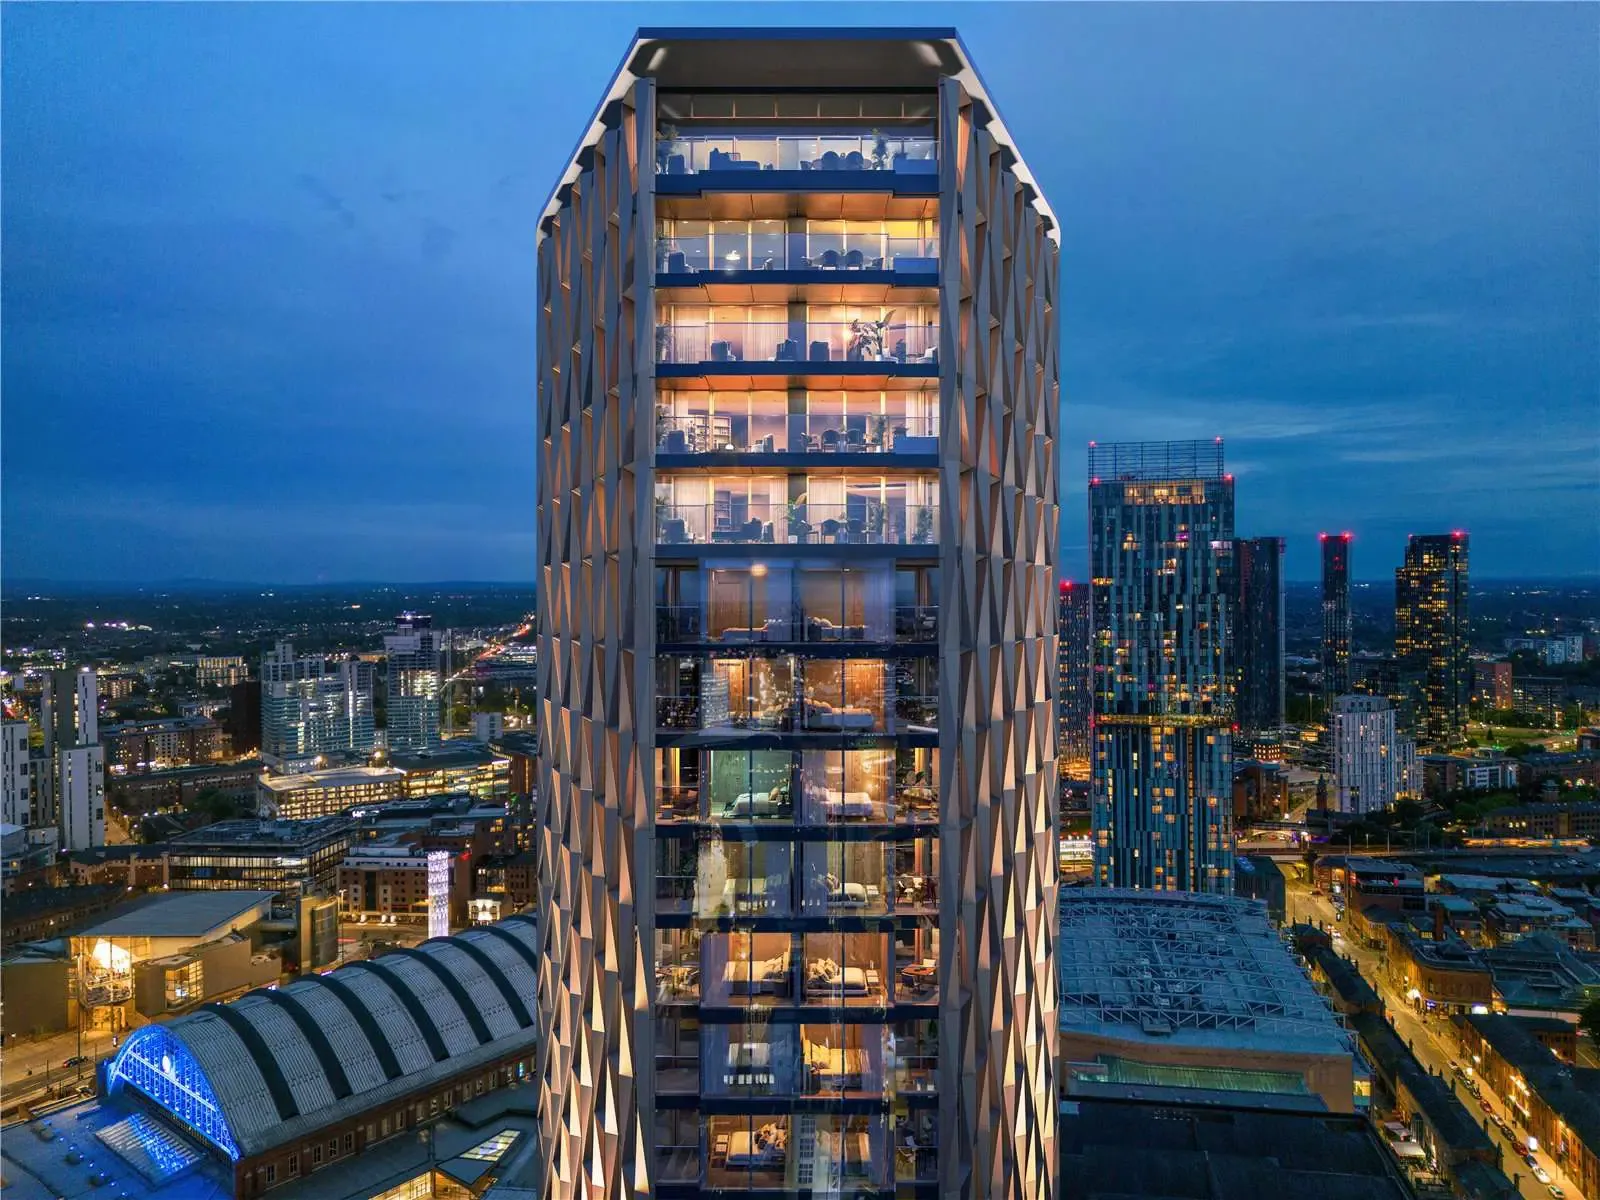
- United Kingdom. New-build apartments in Manchester and Birmingham, with deep rental demand and a 10-year structural warranty on new homes. See our UK buying guide.
- Thailand. Phuket condominiums and villas, many with hotel-run rental programmes. See our Thailand buying guide.
- Malaysia. Lower entry prices, a long-stay visa route and a common-law legal system. See our Malaysia buying guide.
- Spain. The Costa del Sol and Ibiza, with freehold title and a strong resale market. See our Spain buying guide.
Planning the purchase
- Currency. Decide when to convert dollars, and whether to fix the rate for staged payments.
- Financing. Most off-plan in our markets is bought with cash or developer plans. Local mortgages for non-residents are limited.
- Structure. Buying personally is simplest for US reporting. Foreign companies add filings.
- Management. Choose the rental manager before completion, not after.
Next step
The right off-plan purchase starts with the developer, not the view. Our advisers will show you the developments we rate in each market, with the payment plans and the paperwork, and introduce you to independent lawyers on the ground.