
In this story11 chapters
- 01Your passport does not decide the 2%
- 02What an HDB flat or condo adds
- 03Funding: CPF, bonuses and share awards
- 04NRIC, employment pass and IRAS papers
- 05Singapore's foreign-income exemption and the UK
- 06Leasehold, tenants and the rules you inherit as a landlord
- 07Singapore dollars into sterling
- 08Working across a seven- or eight-hour gap
- 09Price forecasts for the North West
- 10简体中文摘要
- 11Our role for Singapore buyers
Singapore buyers of UK property are usually one of two people: a Singaporean adding a sterling asset, or a British expat keeping a foothold at home. Both are normally non-resident for UK stamp duty, and both often own an HDB flat or a condo. That combination sets the cost, so this guide starts with it.
Your passport does not decide the 2%
Stamp duty residence counts days, not nationality. If you spent fewer than 183 days in the UK during the 12 months before the purchase, you are non-resident and pay the 2% surcharge (GOV.UK). A British citizen on an employment pass is in exactly the same position as a Singaporean.
The test is separate from your residence for UK income tax, and the two can give different answers for the same person. If you return to the UK and spend 183 days there within a qualifying 365-day period, the 2% can be reclaimed from HMRC (GOV.UK). Keep a record of your travel dates from the day you complete.
What an HDB flat or condo adds
England's higher rates for additional dwellings count residential property you own anywhere, so an HDB flat or private condo in Singapore counts (GOV.UK). Unless the UK purchase replaces your main residence, that adds 5% of the whole price on top of the 2%.
Take a £200,000 flat. The standard bands give £1,500. A non-resident who owns nothing anywhere, for instance an expat who sold up before leaving and now rents in Singapore, pays £5,500. A non-resident who owns an HDB flat or condo pays £15,500. At this price the surcharges are more than nine times the base tax (our calculations from GOV.UK rates).
Singapore's own stamp duties for foreign and additional buyers apply to Singapore property; they play no part in a UK purchase. The UK band table is on our costs and taxes page, and the stamp duty calculator runs any price.
Funding: CPF, bonuses and share awards
CPF savings are intended for property in Singapore, so they generally cannot fund a UK purchase; check your own case with the CPF Board. A UK purchase is therefore paid from cash, investments, a bonus or the sale of vested shares, or with a UK mortgage. Non-resident lending needs a bigger deposit than a UK buyer would put down, and our mortgages and finance guide explains how it works.
NRIC, employment pass and IRAS papers
A UK solicitor has to verify you and trace the money before accepting it; the standard checklist sits in our buying guide. The Singapore-specific papers are:
- NRIC for citizens and permanent residents, or your employment pass if you are an expat, with your passport.
- Proof of your Singapore address: a recent utility bill or bank statement in your name.
- Employment income: contract, recent payslips and your IRAS notice of assessment.
- Bonuses or share awards: the award statement and the record of sale.
- Sale of a Singapore property: the sale agreement and completion statement.
- Business income: your ACRA business profile, company accounts and dividend records.
- Investments: brokerage statements showing the sale and the proceeds.
- Help from family: a signed gift letter, plus the donor's identity and source-of-funds documents.
Singapore's foreign-income exemption and the UK
Singapore generally exempts foreign-sourced income received by resident individuals, other than through a partnership, and it has no capital gains tax. For most individual owners, UK tax is therefore the only tax on the rent.
The UK side cannot be avoided. Your letting agent keeps back 20% of each rent payment for HMRC, under the scheme for landlords abroad, until HMRC agrees that you may be paid in full; a later sale is caught by capital gains tax for non-residents. Costs and taxes explains both. A UK–Singapore double taxation agreement exists (GOV.UK), yet UK land and buildings stay taxable in Britain under it.
Owning through a Singapore company reopens the question in both countries. Singapore applies its own rules to a company's overseas income, and in the UK any company pays the extra 5% on a home and must be entered on the Register of Overseas Entities before it can buy (GOV.UK). Wherever you live, UK inheritance tax still reaches the flat, so a UK will covering it spares your family delay.
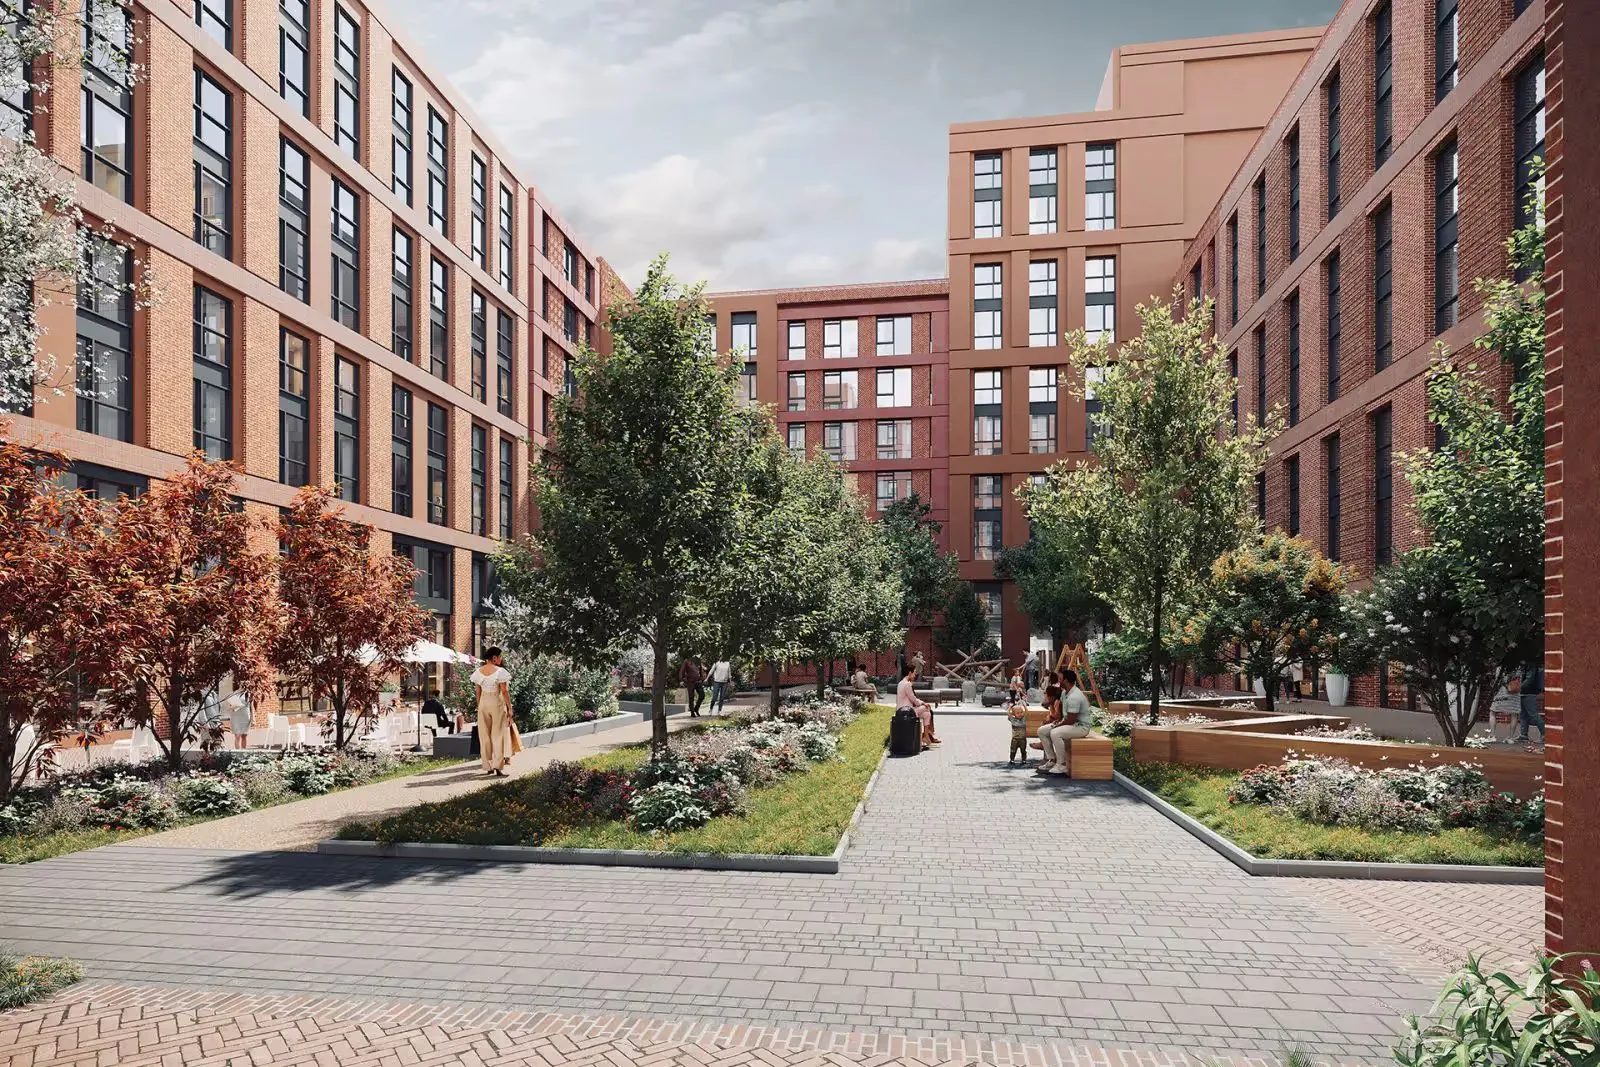
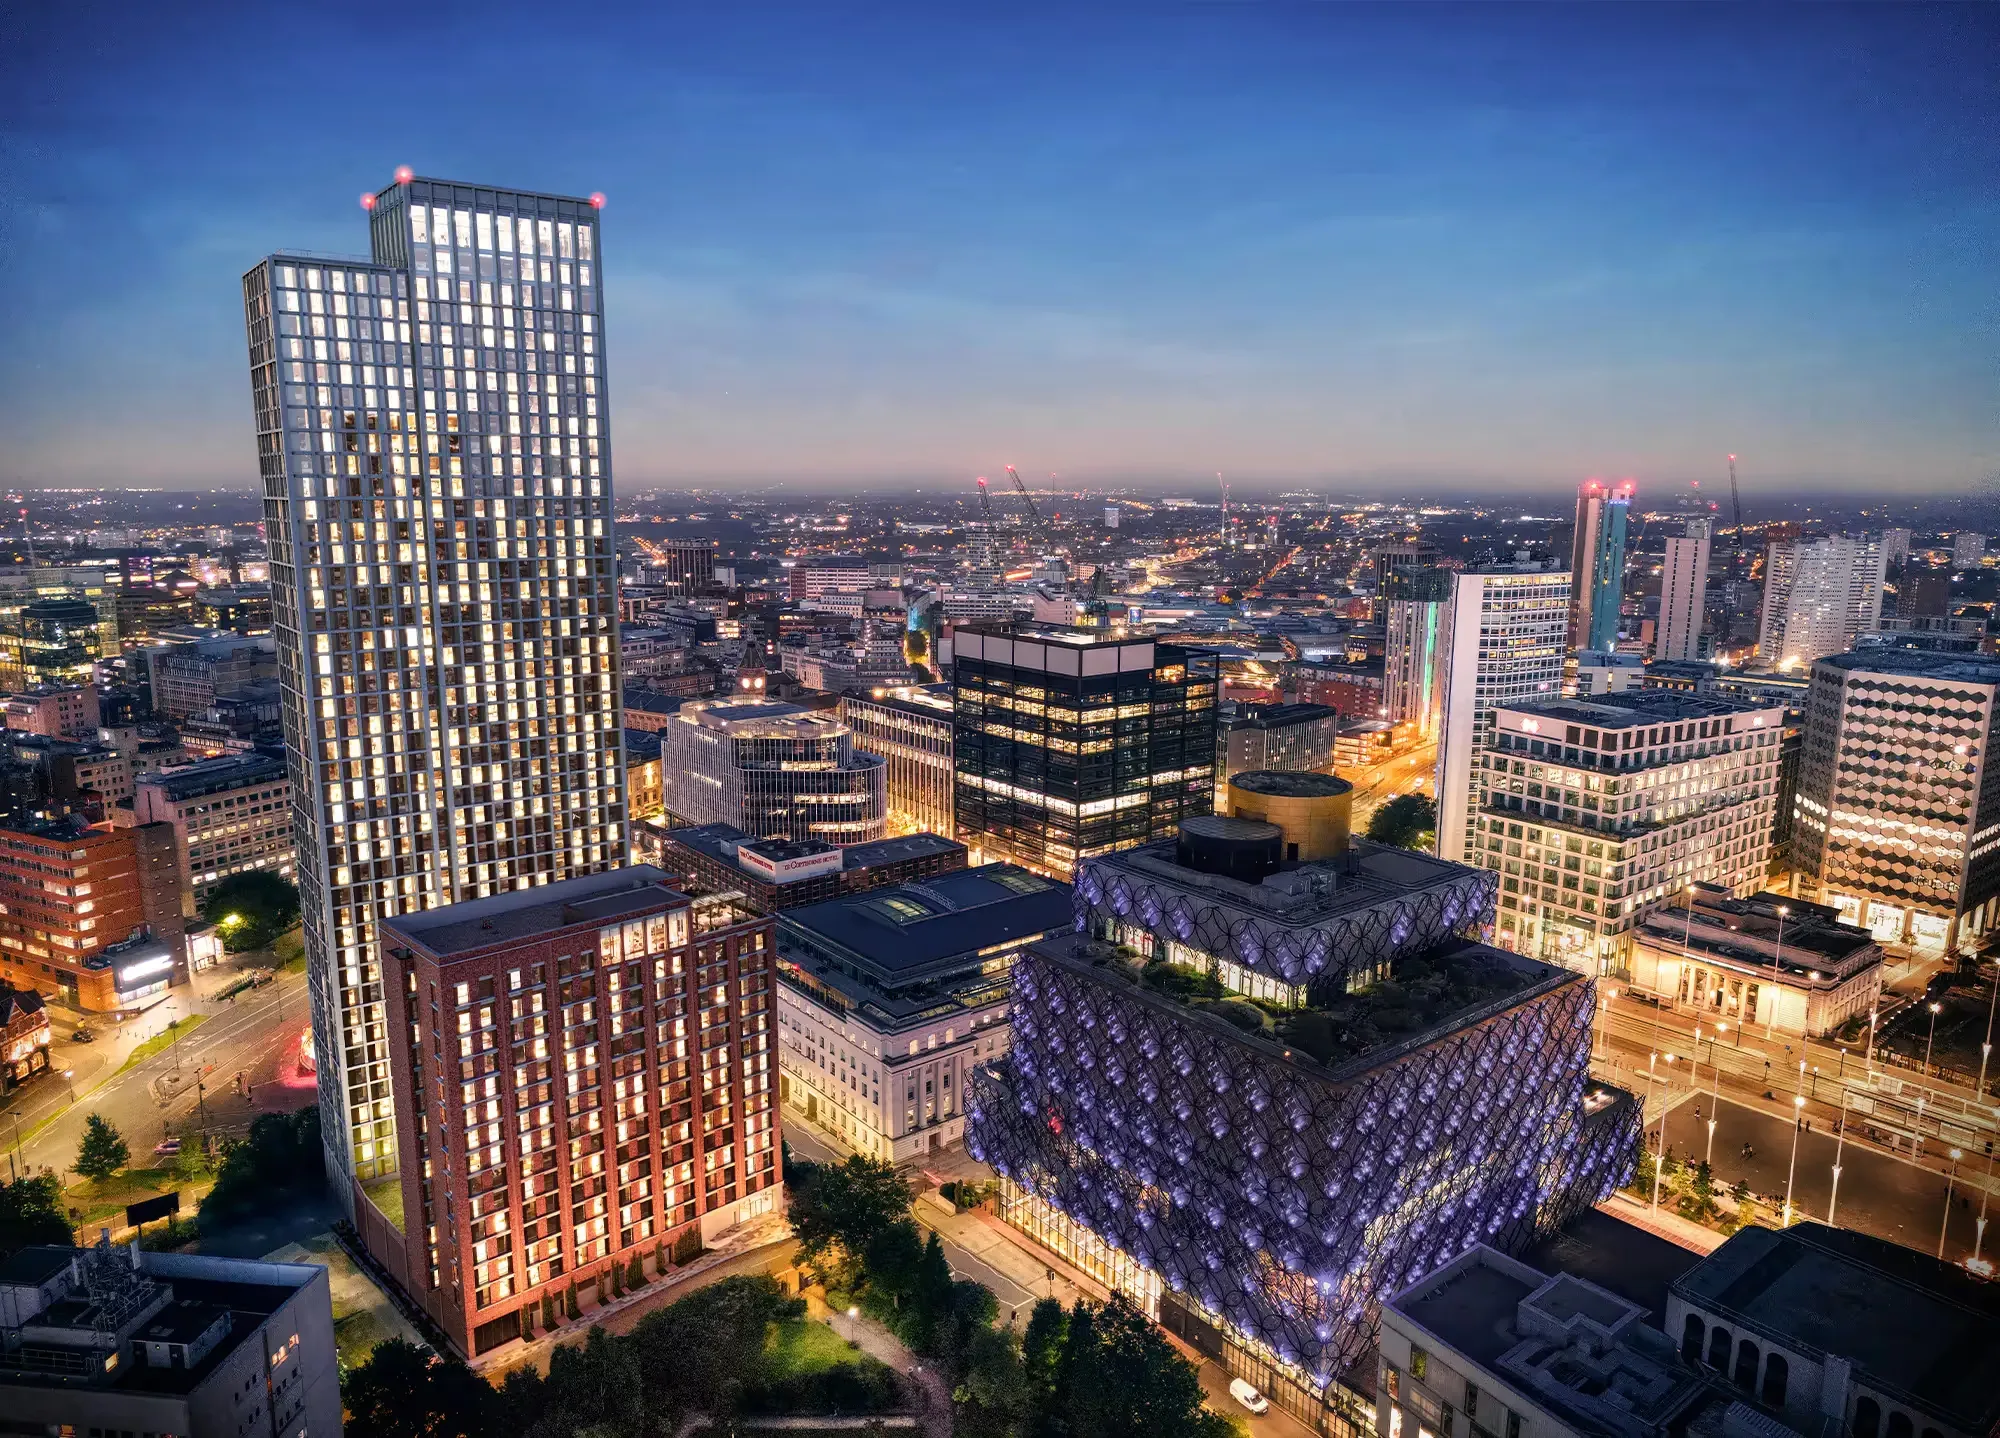
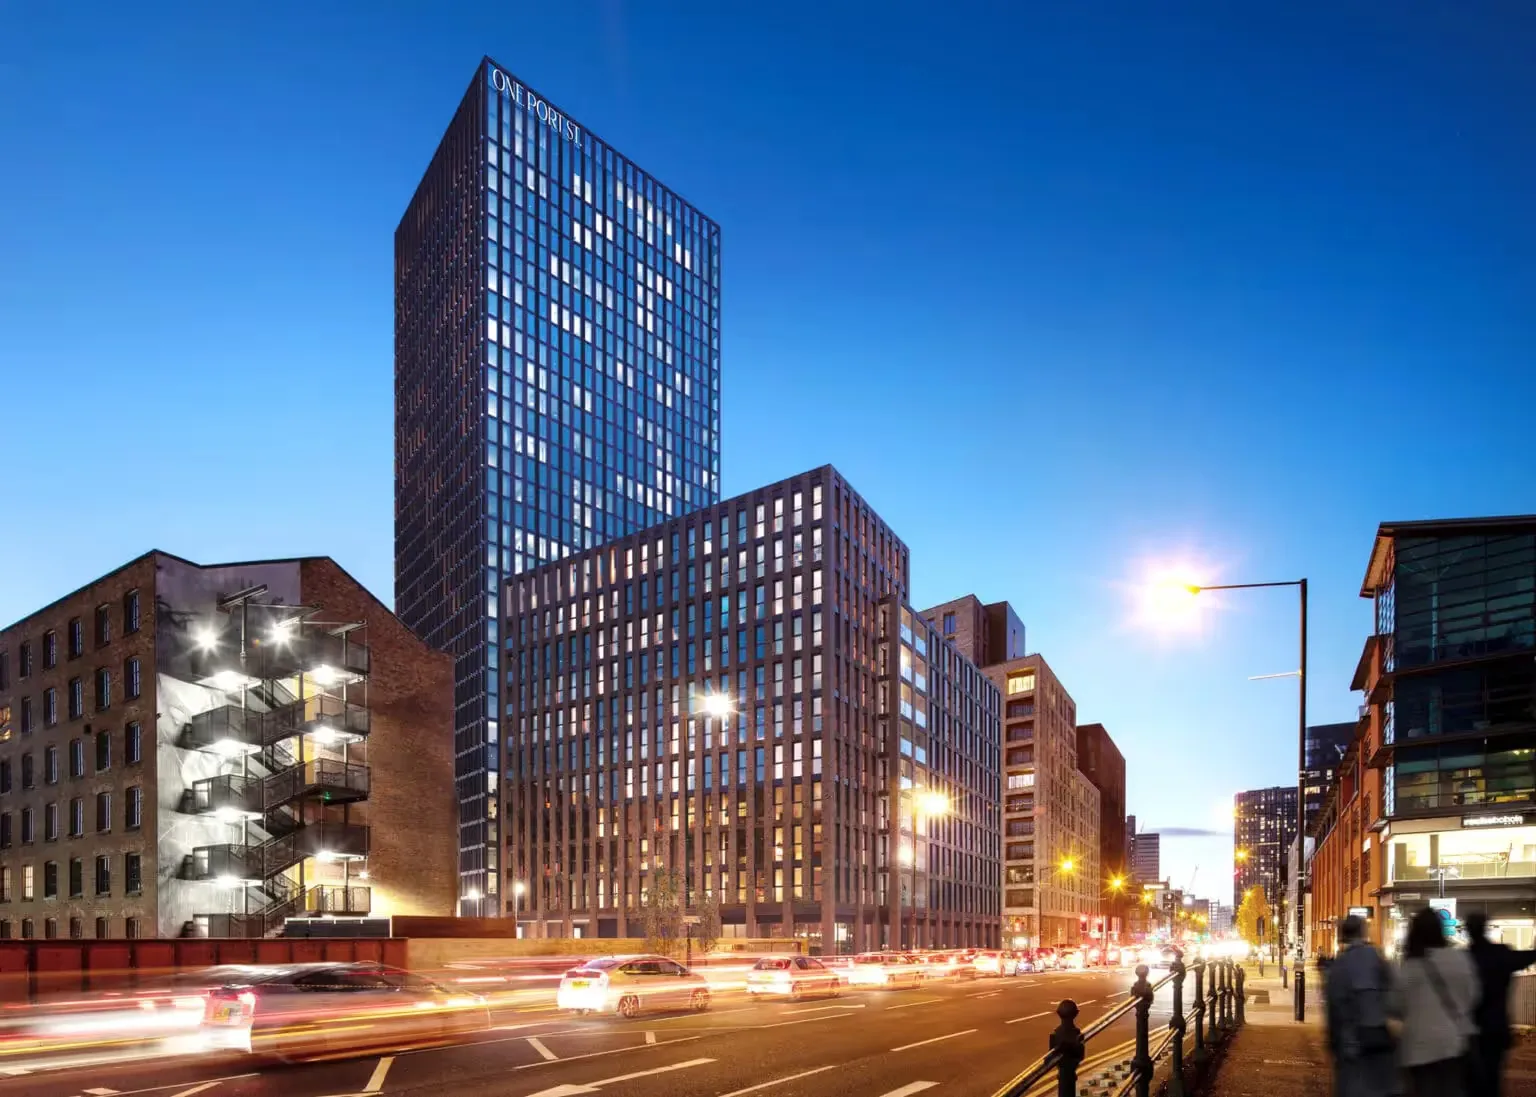
 On the market in United KingdomSmithfield HouseBirmingham, United KingdomFrom £229,995See the development
Leasehold, tenants and the rules you inherit as a landlord
Leasehold will be familiar from Singapore. In England flats are normally sold leasehold too, and on new leases ground rent is capped at a peppercorn by the Leasehold Reform (Ground Rent) Act 2022, so check the lease terms on any resale flat before you reserve. Our foreign ownership guide explains the tenures.
Letting law changed in 2026. The Renters' Rights Act 2025 received Royal Assent on 27 October 2025 and its core provisions came into force on 1 May 2026: section 21 "no-fault" evictions are abolished and tenancies are periodic. A database of private landlords is due in late 2026. Your lettings agent runs these obligations day to day, but as owner you are the landlord of record, even from Singapore.
Singapore dollars into sterling
Your currency risk is the Singapore dollar against the pound. Every price we send is in sterling; any conversion printed here would be stale within days, so we agree it with you when you are ready to buy. Buying off-plan, you can ask a currency specialist for a forward contract dated to completion. And before money leaves your account, call your solicitor using contact details you obtained independently, never ones from a fresh email, to check where it is going.
Working across a seven- or eight-hour gap
From late October to late March, Singapore runs eight hours ahead of Britain; during British Summer Time the gap narrows to seven. Mornings in England are afternoons for you, and that is when most of our calls take place. Contracts are signed electronically and viewings are by live video, so you need not fly at any stage. The purchase stages are in our buying guide; message an adviser from the WhatsApp button on this page.
Price forecasts for the North West
Savills forecasts mainstream prices in the North West to rise 25.0% over the five years to 2030, against 18.5% for the UK as a whole (June 2026). A forecast is not a guarantee, so weigh it against today's income. Our rental yields guide compares current gross yields city by city, and the Manchester guide covers the neighbourhoods.
简体中文摘要
新加坡居民可以在英国购买房产,不受外国人拥有权限制。印花税(SDLT)的居民身份按在英国的天数判定,与国籍无关,因此居住在新加坡的英国公民通常也须缴纳2%非居民附加税。组屋或私人公寓同样计入5%额外房产附加税(GOV.UK)。以200,000英镑的公寓计算:拥有新加坡住宅的买家须缴15,500英镑,在任何地方都没有住宅的非居民买家为5,500英镑。
公积金(CPF)一般不能用于购买英国房产。新加坡一般豁免个人收到的境外收入,但英国租金须在英国纳税。欢迎通过WhatsApp联系我们的顾问。
Our role for Singapore buyers
We show you the stamp duty with your Singapore home counted, confirm whether a return to the UK could earn back the 2%, and keep the solicitor, broker and lettings agent moving while you stay in Singapore.
This guide is general information, not tax, legal or financial advice. Rates change; we confirm current figures before you commit.
Rental yields · Stamp duty calculator · Mortgages and finance · Costs and taxes