
In this story10 chapters
Hong Kong buyers tend to arrive with one of two plans: let a UK flat from Hong Kong, or buy a home for a move to Britain. Between the two, the stamp duty can differ by tens of thousands of pounds, and the timing of your Hong Kong sale is often what decides it.
Investor or mover?
Hong Kong residents can buy freehold houses and leasehold flats in the UK whatever their passport, on the same terms as a British buyer; tenure and the legal process are in our foreign ownership guide. Buying gives no right to live here. Residence comes through a visa, and our visa and residency guide covers the routes.
If you are staying in Hong Kong, you buy as a non-resident who owns a home elsewhere, and both surcharges apply. If you are moving, the two surcharges behave differently: one can be refunded later, the other may never be charged. That is why the order of events matters.
Two questions sort most buyers. What will you own on the day the UK purchase completes? And where will you be living twelve months after it? A buyer who keeps a Hong Kong flat and stays put is an investor. A buyer who sells, moves and lives in the new home is a mover. Some families sit in between, with one spouse moving first, and that is where advice before reservation pays for itself.
The order of sale and purchase, worked through
Take a £450,000 house. At the standard bands, the stamp duty is £12,500 (our calculations from GOV.UK rates throughout this section).
- Keep the Hong Kong flat and buy from Hong Kong. The 5% higher rates apply because you own a home elsewhere, and the 2% applies because you have spent fewer than 183 days in the UK in the past year. Total: £44,000.
- Sell the Hong Kong flat first, so the UK house replaces your main residence. The 5% may not apply. You still pay the 2% if you complete before the move: £21,500.
- Then live in the UK. Spend 183 days here within a qualifying 365-day period and reclaim the 2%, £9,000, from HMRC (GOV.UK). Net cost: £12,500.
The gap between the first line and the last is £31,500. The replacement rules come with detailed conditions, so plan the sequence with your solicitor before you reserve. The full band table is on our costs and taxes page, and the stamp duty calculator handles other prices.
Letting from Hong Kong
If you are staying put, a lettings and management agent handles tenants, rent collection, safety checks and repairs, and we confirm their fees for the scheme you choose. The agent also withholds 20% basic-rate tax under the Non-Resident Landlord Scheme unless HMRC approves you to be paid gross. That scheme, capital gains tax on a later sale and inheritance tax are explained in costs and taxes.
If you move into the home yourself, there is no rent to tax and the agent drops out; if you let it until your move date, agree the tenancy terms around that date with the agent from the start.
Borrowing from Hong Kong is possible through lenders that lend to non-residents, at a larger deposit than a UK resident would need. Once you are living and working in the UK, more lenders and lower deposits may become available; mortgages and finance sets out the difference.
HKID, BN(O) passport and the Hong Kong paper trail
Your solicitor must verify you and trace your money before taking a payment; the standard list is in our buying guide. From Hong Kong, expect to provide:
- Hong Kong identity card, with your HKSAR or BN(O) passport, for every buyer and contributor.
- Proof of your Hong Kong address: a recent utility bill or bank statement in your name.
- Salary: employment contract and recent payslips, or your salaries tax assessment.
- Sale of a Hong Kong flat: the sale and purchase agreement and the completion statement. For a mover funding the UK home from that sale, this is the core of the file.
- Provident fund or pension withdrawals: the scheme statement showing the payment.
- Business income: business registration, company accounts and dividend records.
- Money from a parent or spouse: a signed gift letter, with the donor's identity and source-of-funds papers.
Territorial tax and the treaty
Hong Kong taxes on a territorial basis. Its property tax applies to property in Hong Kong, so rent from a UK flat you own personally is generally outside it, and Hong Kong has no capital gains tax. For a personal owner, the UK is normally the only place the rent is taxed.
A Hong Kong company changes that. Profits tax and Hong Kong's rules on foreign-sourced income for companies need checking, and on the UK side a company always pays the 5% higher rates and must register on the Register of Overseas Entities before it buys (GOV.UK).
The UK and Hong Kong have a double taxation agreement (GOV.UK). It does not remove UK tax on UK rent or gains, but it matters more once you move and become UK resident, when your worldwide income comes into the UK's view. Take UK tax advice before the move rather than after it. A UK will for your UK assets also saves your family delay.
 On the market in United KingdomSmithfield HouseBirmingham, United KingdomFrom £229,995See the development
The Hong Kong dollar and sterling
Because the Hong Kong dollar is linked to the US dollar, a UK purchase leaves you exposed to the pound against the dollar. Prices reach you in sterling. If you are buying off-plan to move into later, a forward contract can hold the rate until completion. A mover may make two large transfers close together, the Hong Kong sale proceeds and the UK completion money, so check your solicitor's account by phone before each one.
An eight-hour gap
Hong Kong clocks sit eight hours ahead of London in the British winter and seven in the British summer. An English morning catches the end of your working day, and a 4pm call in Manchester is late evening in Hong Kong. Documents are signed electronically, so the time difference costs nothing. The stages to completion are listed in our buying guide; message an adviser on WhatsApp from this page.
Supply in Manchester
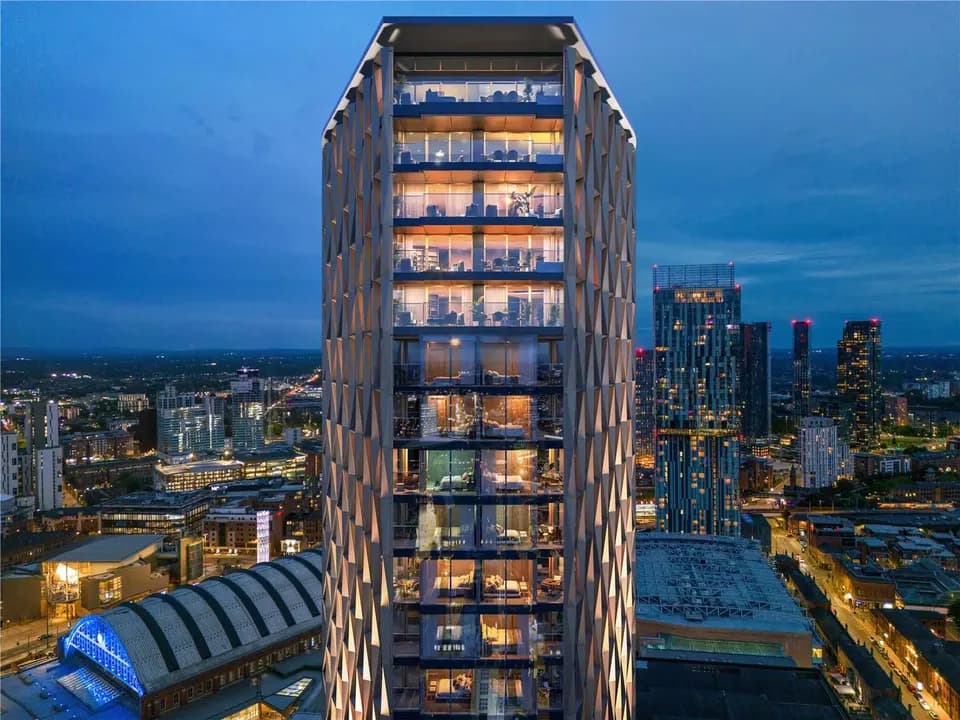
Deloitte's 2026 Manchester Crane Survey counted 8,023 homes under construction, the first time below 10,000 since 2016, with 15,332 more consented but not started. The same survey recorded 3,422 completions in 2025 and forecast around 5,500 for 2026. Fewer homes under construction can mean fewer new flats competing for tenants as they complete, and less choice for buyers. Our Manchester guide covers the neighbourhoods, and the rental yield calculator tests a specific apartment.
繁體中文摘要
香港居民可以在英國購買物業,不受外國人擁有權限制,但購買物業並不賦予在英國居留的權利。以450,000英鎊的物業計算:保留香港住宅並在香港置業,印花稅(SDLT)為44,000英鎊;如先出售香港自住物業,而英國物業取代您的主要住所,5%附加稅可能不適用,印花稅為21,500英鎊;其後在合資格的365日內在英國居留183日,可向HMRC申請退回9,000英鎊非居民附加稅(GOV.UK)。
香港按地域來源原則徵稅,個人持有的英國物業租金一般不在香港物業稅範圍內,但須在英國繳稅。英國律師會要求香港身份證、護照(包括BN(O)護照)及資金來源文件。歡迎透過WhatsApp聯絡我們的顧問。
How we work with Hong Kong clients
We price both plans, staying or moving, with the stamp duty for each. If you are relocating, we line up the UK purchase with the sale of your Hong Kong flat so the sequence works in your favour.
This guide is general information, not tax, legal or financial advice. Rates change; we confirm current figures before you commit.
Manchester property · Visa and residency · Costs and taxes · Buying guide