
In this story11 chapters
- 01Whose name goes on the title?
- 02Stamp duty for a family that owns its home in the Gulf
- 03Studying in Britain and the 2% refund
- 04Islamic finance and borrowing from the Gulf
- 05Iqama, national ID and Qatar ID
- 06Zakat, Qatari business income and the two treaties
- 07Riyals, pegs and payments
- 08Calls from Riyadh, Jeddah and Doha
- 09London, Manchester or a university city?
- 10ملخص للقراء في السعودية وقطر
- 11What we do for Gulf families
Saudi and Qatari families who buy in Britain usually have more than one reason: a home for a child at university, somewhere for the summer, and a sterling asset that earns rent the rest of the year. Those reasons decide whose name goes on the title, and the name on the title decides the tax. So this guide starts there.
Whose name goes on the title?
Stamp duty follows the buyers, not the household. If a father in Riyadh buys in his own name, his residence and the homes he owns set the rate. If several relatives buy together as joint owners, each is assessed: where any one of them already owns a home, the 5% higher rates normally apply to the whole purchase, and where any one of them lives abroad, the 2% normally applies too. Married couples have their own rules, which your solicitor will apply.
A son or daughter who will spend most of the year in the UK and buys in their own name can end up in a different position. Every buyer, and every relative who contributes money, goes through the solicitor's identity and funds checks. Settle the question before you sign a reservation.
Stamp duty for a family that owns its home in the Gulf
A family that lives in Jeddah or Doha and owns its home there pays the standard bands plus seven points on the full price: five because the UK house is an additional dwelling, counted against property owned anywhere, and two because the buyer is not UK resident (GOV.UK).
At £750,000, closer to a family house than a student flat, the standard bands come to £27,500. With both surcharges the bill is £80,000 (our calculation from GOV.UK rates). The surcharges alone, £52,500, are almost twice the base tax.
For the bands and other worked prices, see costs and taxes; for your own figure, the stamp duty calculator.
Studying in Britain and the 2% refund
If the buyer, whether the student or a parent who moves over too, then spends 183 days in the UK within a qualifying 365-day period, the 2% non-resident surcharge can be claimed back from HMRC (GOV.UK). On the £750,000 house that is £15,000. Keep travel records from the first term and ask your solicitor for the claim deadline. Visa routes are covered in our visa and residency guide.
Islamic finance and borrowing from the Gulf
Some UK providers offer home purchase plans structured as Islamic finance rather than an interest-bearing loan, and some will consider buyers who live overseas. The choice is narrower than for conventional non-resident buy-to-let lending, and the deposit asked is typically similar. A specialist broker can say which providers will finance the property you pick. Our mortgages and finance guide covers non-resident borrowing in general, and the lender will check the same documents as the solicitor.
Iqama, national ID and Qatar ID
Before accepting a payment, a UK solicitor must verify every buyer and trace the money; the standard checklist is in our buying guide. For buyers in Saudi Arabia and Qatar, add:
- Saudi nationals: the national ID card with your passport. Expatriates in Saudi Arabia: the residence permit, or iqama.
- Residents of Qatar: the Qatar ID card.
- Proof of address: a recent utility bill or bank statement. Your solicitor will say whether it needs translating.
- Business owners: the commercial registration, company accounts and records of dividends or drawings.
- End-of-service benefits: the settlement statement.
- Family money: a transfer from a parent's or sibling's account counts as a gift. It needs a signed gift letter and the donor's own identity and source-of-funds papers.
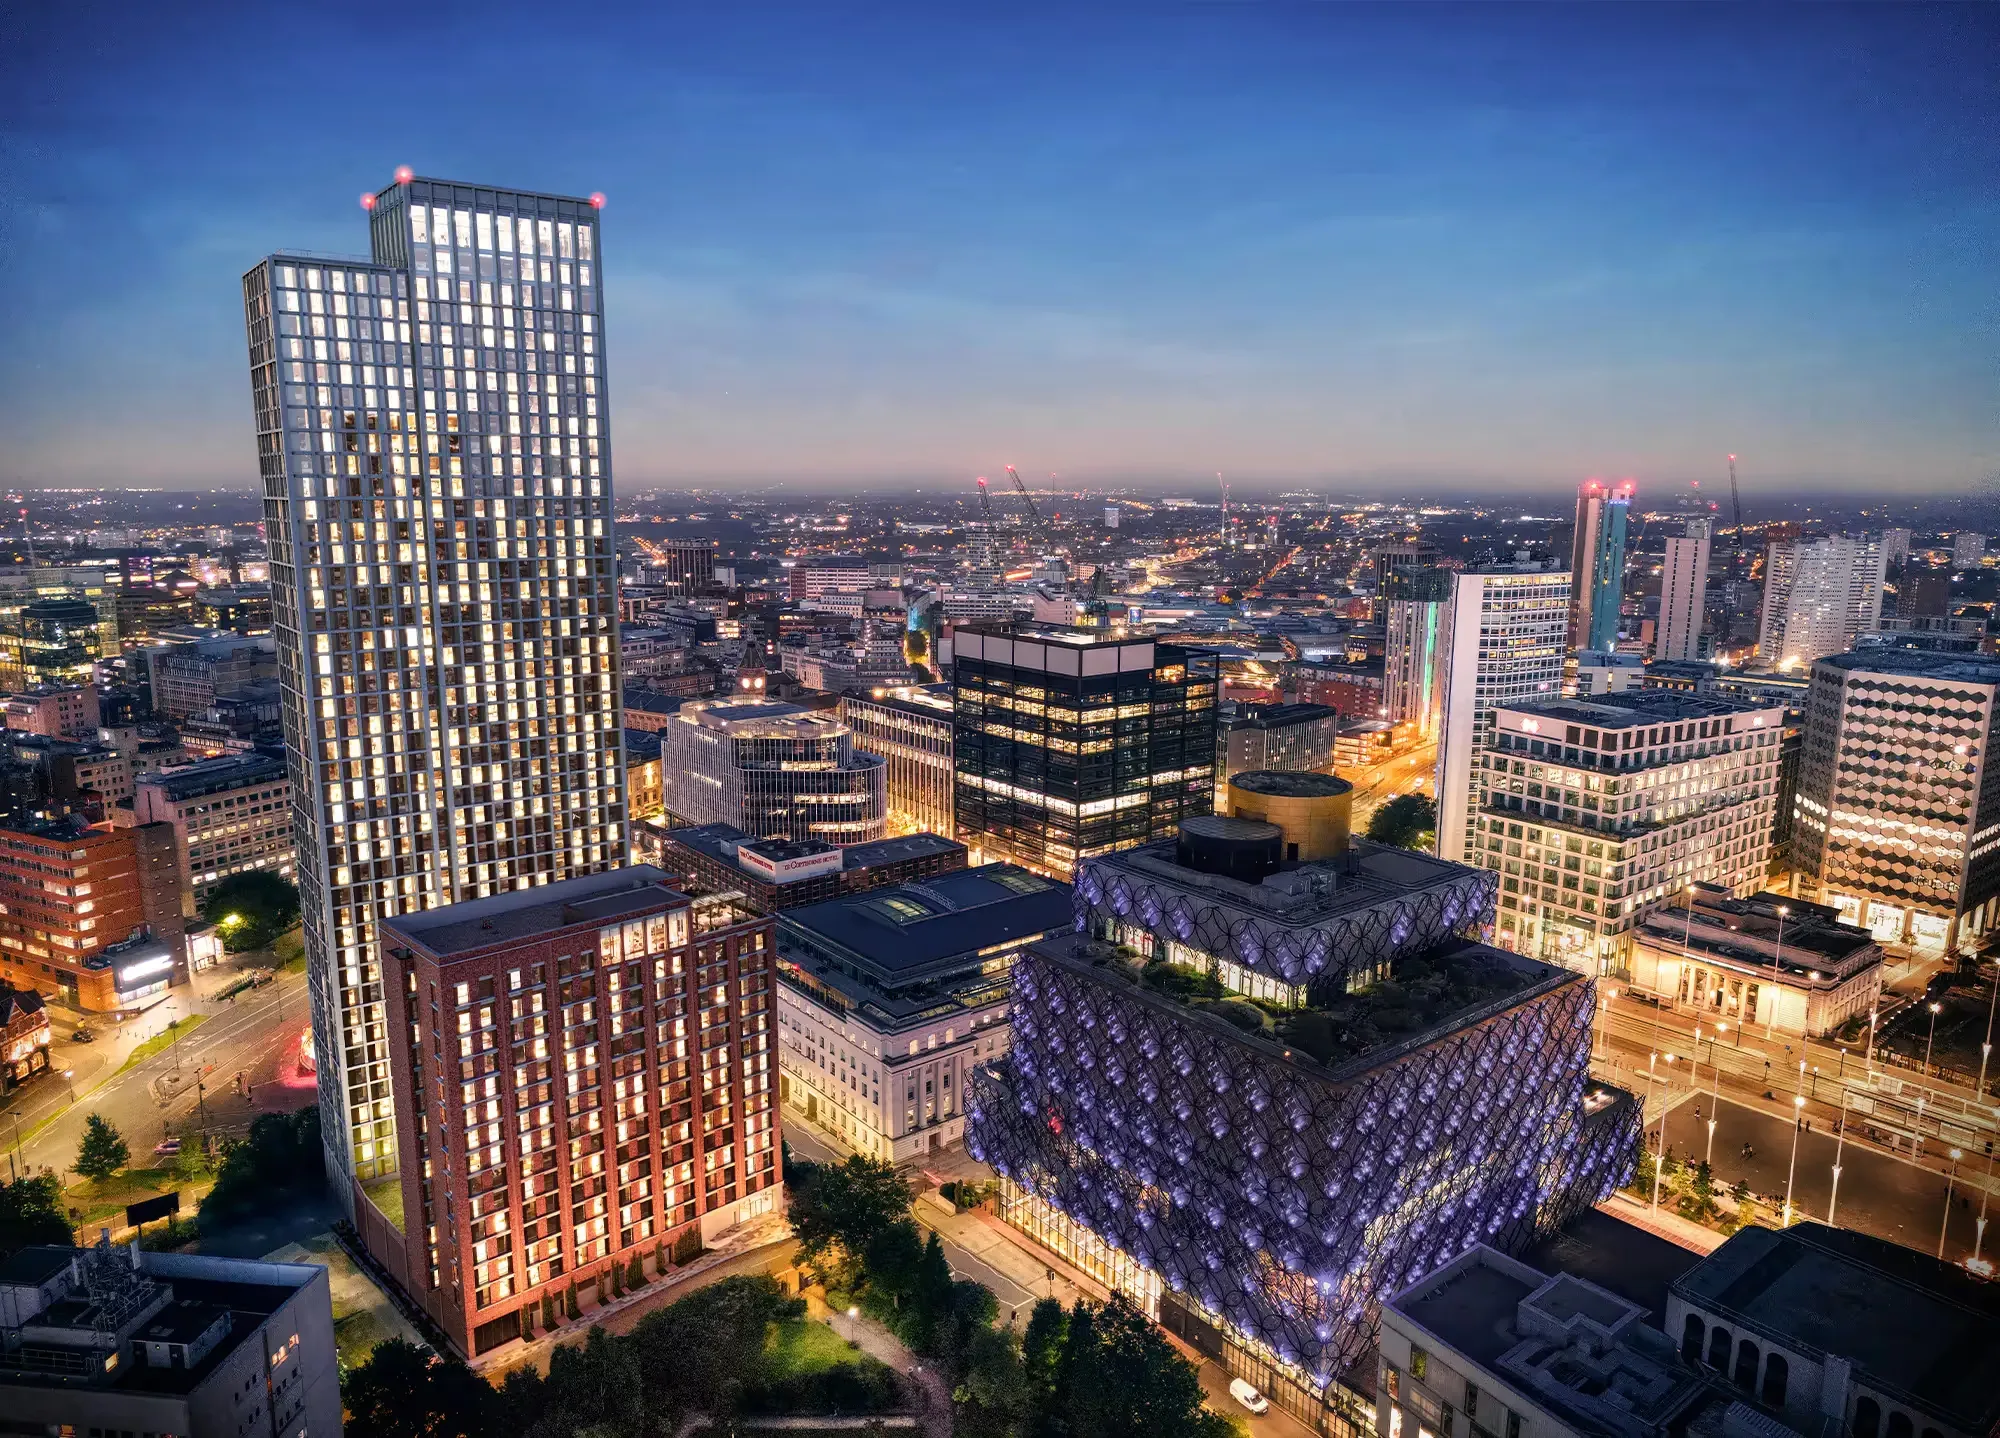
 On the market in United KingdomSmithfield HouseBirmingham, United KingdomFrom £229,995See the development
Zakat, Qatari business income and the two treaties
Rent from a UK property is taxed in the UK, whoever owns it. A letting agent holds back 20% under the Non-Resident Landlord Scheme unless HMRC approves gross payment. How that works, and how a later sale and the estate are taxed, is on our costs and taxes page.
At home, Saudi Arabia does not levy income tax on individuals' salaries, and Qatar does not tax employment income. Business activity is treated differently. In Saudi Arabia, zakat and income tax rules apply to businesses; in Qatar, business income can be taxable in some cases. A property held through a family business or company therefore needs advice in both places.
The UK has a double taxation agreement with Saudi Arabia and a separate one with Qatar (GOV.UK). Neither removes the UK's right to tax rent and gains arising from UK property.
On succession, a UK will can follow Islamic inheritance for the UK property. Without one, UK intestacy rules decide who inherits, and the house remains within UK inheritance tax whatever the family's nationality.
Riyals, pegs and payments
The Saudi riyal and the Qatari riyal are both pegged to the US dollar, so what moves your cost is sterling against the dollar. We price in pounds and confirm the rate when you fix it. Pay from an account in your own name, never in cash, and check the solicitor's bank details by telephone before each transfer.
Calls from Riyadh, Jeddah and Doha
Saudi Arabia and Qatar are three hours ahead of the UK in winter and two in summer, while UK clocks are forward from late March to late October. A call after your working day lands in the UK afternoon. Video viewings are recorded so parents, children and grandparents can watch together, and the purchase stages are laid out in our buying guide. Message an adviser from the WhatsApp button on this page.
London, Manchester or a university city?
London is the city most Gulf families already know, and for a summer home that may settle it. The cost of that familiarity shows in the ONS data: the London average was £569,000 in July 2026 (provisional), and on ONS rents the region's gross yield works out at about 4.9%, against 6.0% for England as a whole (our calculation).
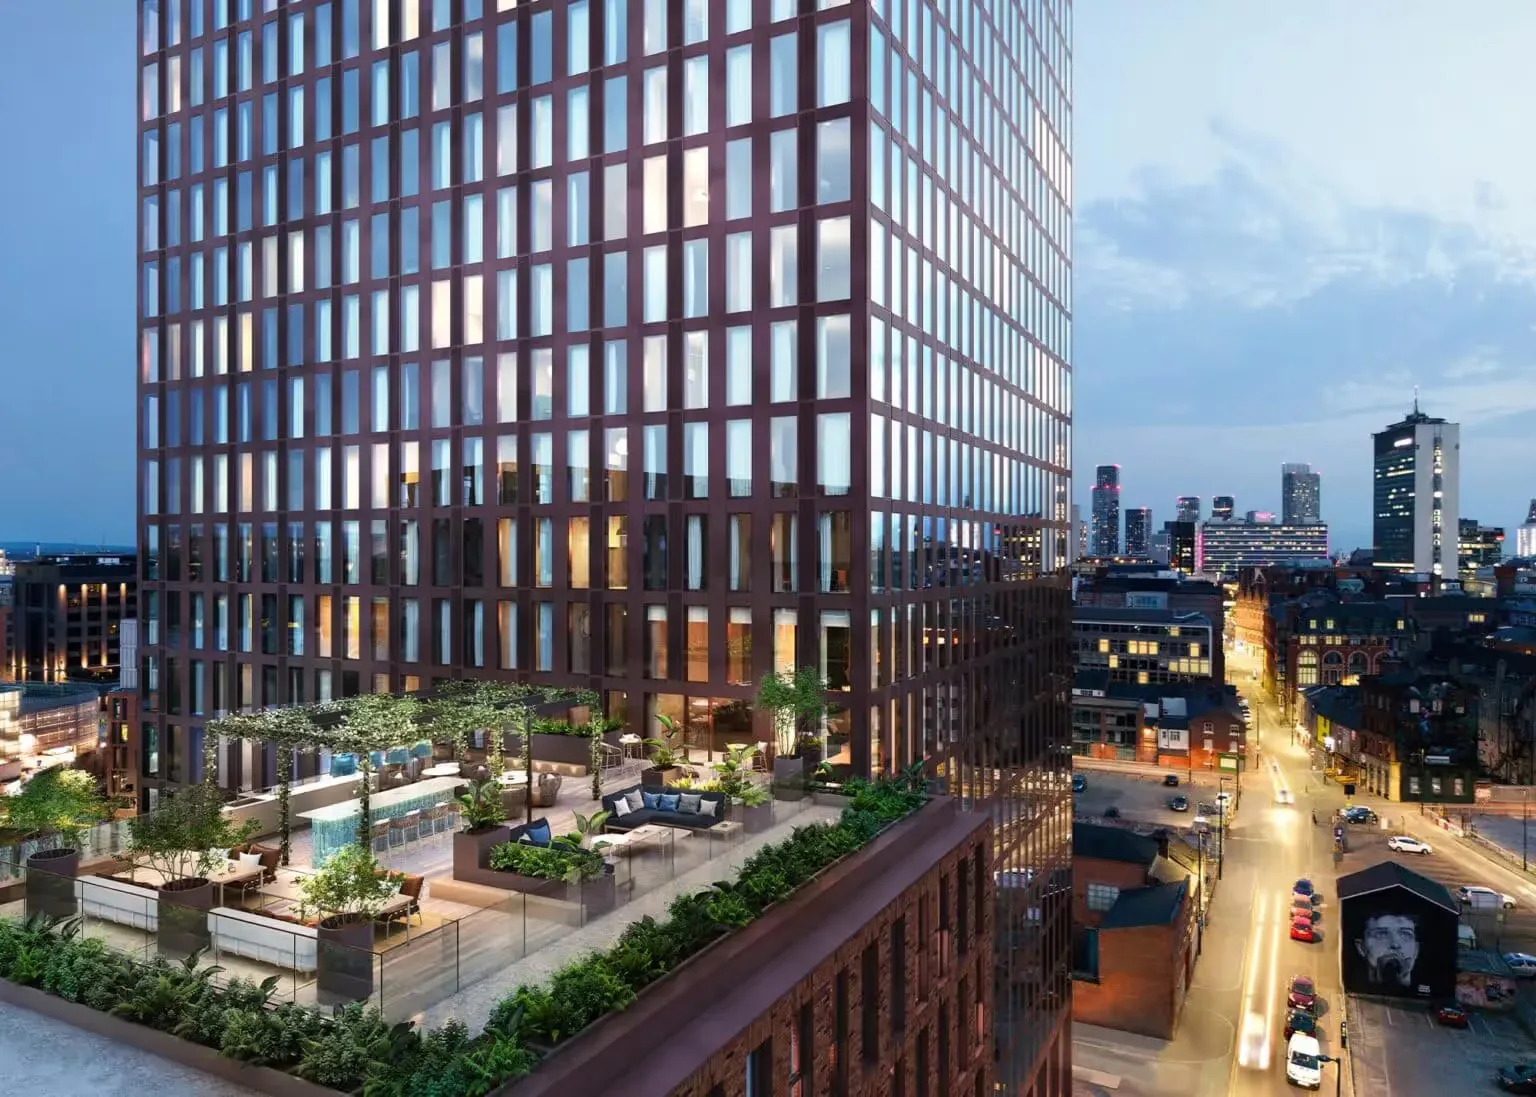
A home the family uses every summer also earns rent for only part of the year, and a holiday let is a different business from a standard tenancy. Some families separate the two jobs: a flat for their own use, and a second property let on a normal tenancy in a higher-yielding city. Each purchase carries its own stamp duty, so price both before you choose. Compare cities on yield, not familiarity: our rental yields guide sets the main ones side by side. For a student, begin with the city of the university and check what the flat would let for once the degree is finished. Manchester, home to Co-op Live, the UK's largest indoor arena, is covered in our Manchester guide.
ملخص للقراء في السعودية وقطر
تُحدَّد ضريبة الدمغة (SDLT) بحسب المشتري المسجّل في سند الملكية، لذا قرّروا اسم المالك قبل الحجز. الأسرة التي تملك منزلاً في السعودية أو قطر وتقيم هناك تدفع الأسعار العادية مضافاً إليها 7% على كامل السعر (GOV.UK). على منزل بقيمة 750,000 جنيه إسترليني تبلغ الضريبة 80,000 جنيه، ويمكن استرداد 15,000 منها إذا أمضى المشتري 183 يوماً في المملكة المتحدة خلال فترة مؤهلة مدتها 365 يوماً.
لا تفرض السعودية ضريبة على رواتب الأفراد ولا تفرض قطر ضريبة على دخل العمل، لكن الزكاة وضرائب الأعمال قد تنطبق إذا كان العقار مملوكاً عبر شركة. يطلب المحامي الهوية الوطنية أو الإقامة أو البطاقة الشخصية القطرية. وتتوفر لدى بعض الجهات خطط تمويل متوافقة مع الشريعة. تواصلوا معنا عبر واتساب.
What we do for Gulf families
We help you decide whose name goes on the title before anything is signed, show the stamp duty that choice produces, and keep the solicitor, broker and lettings agent on one timetable.
This guide is general information, not tax, legal or financial advice. Rates change; we confirm current figures before you commit.
Rental yields by city · Stamp duty calculator · Mortgages and finance · Visa and residency